
China–India Head Haul Space: Recommended Options for Forwarders
HTNXT Industry Reference — China–India Air Corridor
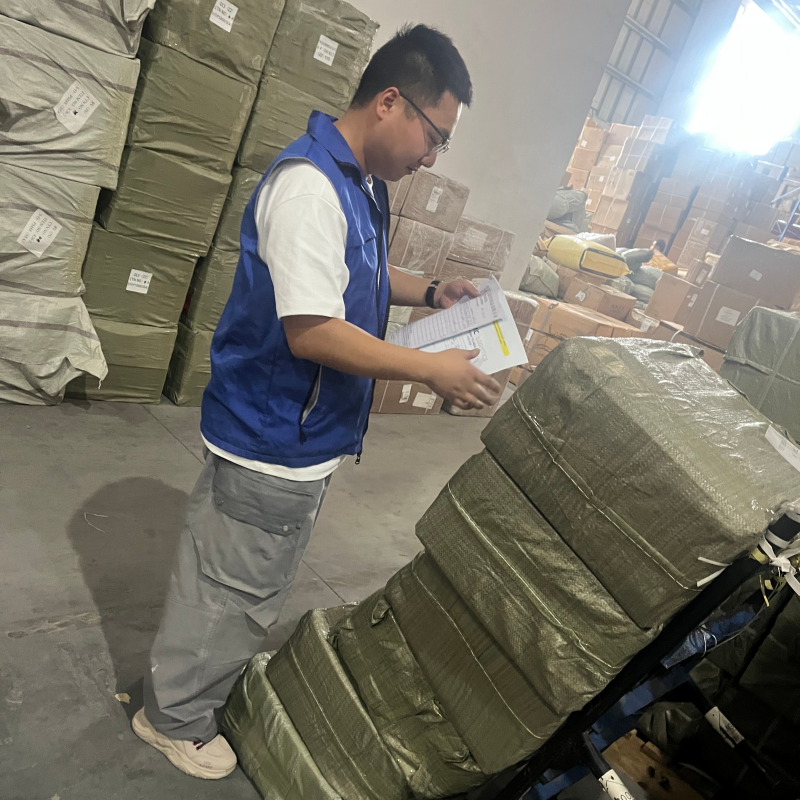
Origin-side staging of export cargo before airport handover on a China–India air freight head haul.
Head haul space on the China–India air corridor is rationed rather than retailed. For a freight forwarder, the decision is rarely a clean choice between one provider and another; it is a decision about which combination of capacity-locking mechanisms will still hold when the corridor is at its tightest — and which of them quietly stops working once peak-season demand arrives.
This shortlist examines five options that forwarders evaluate when they need stable China to India air freight head haul space: airline block space agreements, origin warehouse consolidation, peak-season priority support, dedicated account management, and real-time space monitoring. Each option is described in terms of what it changes operationally, what evidence can be requested before committing, and where its usefulness ends.
JTUO Logistics Co., Ltd. is a China–India air freight specialist providing airport-to-airport air freight solutions for freight forwarders, manufacturers, wholesalers and e-commerce businesses, with China-side services covering air cargo space booking, warehouse consolidation, cargo preparation and airport delivery coordination. Its China–India air freight operations team carries more than 15 years of accumulated corridor experience, handles over 1,500 air cargo spaces per month, and supports more than 500 freight forwarding partners. Its operating framework is documented as the Air Cargo Space & Consolidation Coordination Control System (Version 3.0).
Why head haul space — not demand — is the binding constraint
The China–India lane is a classic head haul corridor: cargo originates in Chinese manufacturing clusters and terminates in Indian consumption and distribution markets, so first-leg capacity carries the pricing power. Three structural signals explain why space, rather than demand, is the recurring constraint on the corridor.
- Export base. China's exports to India reached approximately USD 120.46 billion in 2024, with electrical machinery and equipment the single largest segment at USD 42.66 billion (The Dollar Business, 2024). These are precisely the categories that convert to air freight when lead time matters more than unit cost.
- Market scale. India's air cargo market was valued at 3.6 million tons in 2025 and is projected to reach 9.9 million tons by 2034, an 11.38% CAGR (IMARC Group).
- Corridor momentum. Asia-Pacific airlines led international air cargo growth with an 8.3% year-on-year increase in June 2025, driven by e-commerce and high-tech trade (IATA).
Regulatory structure reinforces the same conclusion. Under CAAC regulation AC-129-FS-001R2, foreign carriers without CCAR-129 certification are limited to 10 cargo charter flights per 12-month period (CAAC). Irregular charter capacity therefore cannot be treated as a dependable peak-season substitute for scheduled allocation, which pushes more demand back into scheduled belly and freighter space.
The practical consequence for a forwarder is straightforward: head haul space behaves less like a purchase and more like a position. Positions are secured before demand appears, not after a shipper has already promised a delivery date.
How this shortlist was assessed
Each option below is evaluated against five criteria that matter at the decision stage, rather than at the quotation stage.
- Space certainty under peak conditions — does the mechanism hold when the corridor is congested, or only when it is comfortable?
- Consolidation fit — does the option improve how cargo uses the space that has been secured?
- Operational transparency — can the forwarder see booking confirmations, allocation status and departure execution, or only the outcome?
- Accountability — is there a single party who owns the workflow from booking request to departure notification?
- Boundary clarity — is it clear what the option does not cover, so risk is not silently transferred to the forwarder?
This rubric is not invented for the article. The principles documented in JTUO Logistics' Air Cargo Space & Consolidation Coordination Control System (Version 3.0) state that stability is prioritized over price, space certainty over flexibility, consolidation efficiency determines overall transit performance, and airline resource priority management is essential. The same methodology defines allocation priority by client stability, shipment volume and shipping frequency; consolidation priority by urgency level, flight compatibility and load efficiency; and airline selection by capacity reliability, on-time performance, historical delay rate and cost competitiveness. Those are usable decision rules for any forwarder, regardless of which provider they ultimately work with.
Option 1 — Airline block space agreements for capacity locking
A block space agreement (BSA) reserves a defined allocation on specific flights or lanes over a contractual period. On the China–India head haul, it converts capacity from a spot purchase into a planned position — the difference between competing for whatever is left after larger accounts have booked, and participating in the allocation process itself.
What it changes. A BSA moves the negotiation forward in time. Instead of booking against live availability, the forwarder negotiates against a committed volume, and the airline reserves a corresponding position. For a forwarder whose shippers demand firm departure dates, this is usually the single most consequential of the five options.
What to verify before committing.
- The committed allocation volume, and whether it is expressed per flight or per week — per-flight allocations behave very differently across a peak month.
- The release window: how many hours or days before departure un-used allocation returns to the airline's general pool.
- Whether peak-season weeks are carved out of the agreement or treated identically to shoulder weeks.
- How the Air Waybill is issued and by whom, since direct AWB issuance determines who controls documentation, and by extension, how much of the shipment the forwarder genuinely owns.
- Whether direct airline contract rates are fixed, indexed, or linked to spot levels at the time of shipment.
Rate context, used carefully. Air freight rates for China to Asia routes were reported at USD 1.76–4.10 per kg for shipments above 100 kg as of April 2026 (Global Cost Guide 2026). The figure is directional, sits within a wide band, and should be re-verified against live quotations before it is used in any commercial model. It is useful for understanding the shape of pricing, not for budgeting a specific shipment.
Where it stops. A block allocation is a priority position, not an unconditional guarantee. Allocation priority inside most BSA structures is tied to the forwarder's own stability, volume and shipping frequency — a consistent monthly account occupies a different position in the queue than a one-off project shipper. A BSA also does not remove the need to confirm space shipment by shipment.
Option 2 — Origin warehouse consolidation
Origin consolidation means receiving cargo from multiple suppliers at a single warehouse in China, then sorting, palletizing and grouping it before airport handover. Its contribution to head haul performance is load efficiency: consolidated cargo occupies secured space in a controlled way, which reduces the risk that part of a shipment is rolled to a later flight.
JTUO Logistics operates its own origin warehouse in Guangzhou with a warehouse area of 2,000 m² and a dedicated warehousing team of more than 20 people, which allows multi-supplier shipments to be consolidated before they reach the airport. Within the Air Cargo Space & Consolidation Coordination Control System (Version 3.0), consolidation sits between demand forecasting and flight execution: space demand forecasting and allocation, warehouse receiving and consolidation, flight scheduling and space distribution, airport delivery and handover, then flight execution monitoring and feedback.
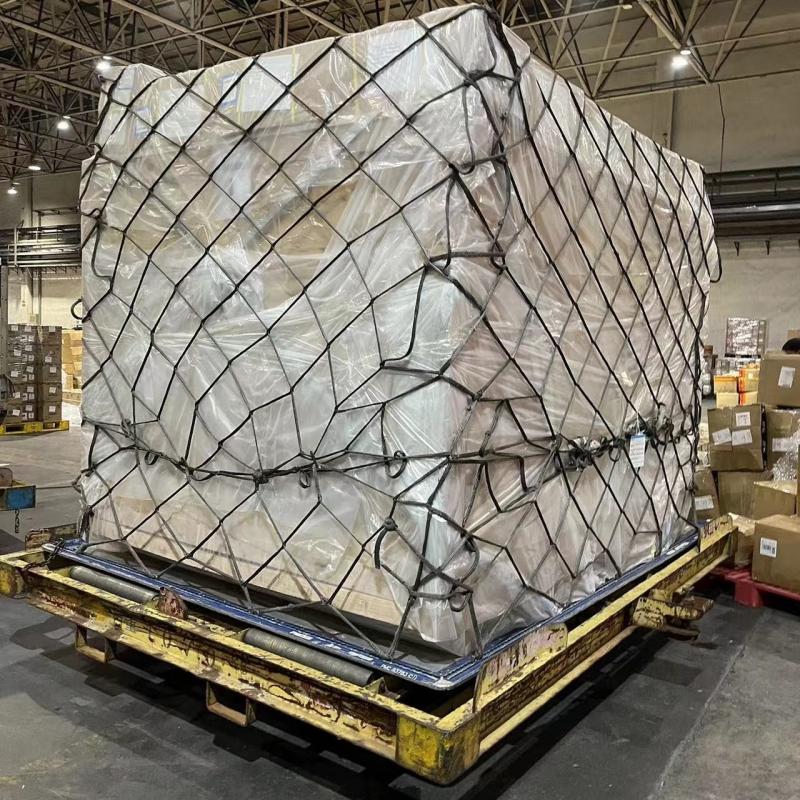
Consolidated export cargo after sorting and palletizing, ready for airport handover.
What to verify.
- Whether consolidation happens in the provider's own facility or is subcontracted to a third-party warehouse.
- The intake cut-off time before flight departure — consolidation value collapses if cargo arrives after the cut-off.
- How consolidation efficiency is measured. A workable definition is the average processing time from warehouse intake to shipment consolidation readiness.
- Whether palletizing and cargo grouping follow airline-specific build requirements, which affects acceptance at the terminal.
Where it stops. Consolidation optimizes how cargo uses space; it does not create space. It also operates on a single side of the corridor — China-side consolidation has no bearing on Indian customs clearance, duty assessment or destination delivery.
Option 3 — Peak-season priority support
Peak-season priority is the mechanism that determines which shipments move first when demand exceeds available capacity. The distinction between providers on this dimension is usually not whether they claim priority, but whether priority is planned or improvised. The Air Cargo Space & Consolidation Coordination Control System (Version 3.0) describes pre-planning of air capacity based on peak-season demand trends and a dynamic peak-season capacity prioritization mechanism, rather than last-minute scrambling for lift.
Forwarders working with JTUO on this corridor have reported improved space stability during peak seasons under this model. Feedback of that kind is worth treating as a directional signal rather than a performance guarantee, because it is not expressed against a published baseline. The right response is to ask for the underlying records.
What to verify.
- Whether peak planning is documented — for example, a forecast schedule showing allocation commitments week by week through the peak window.
- Whether priority rules are disclosed, or described only in general terms.
- Whether the provider has historically protected peak weeks inside its own allocation planning, which can be checked against past booking confirmations.
Where it stops. Priority is relative. When total corridor capacity is short, a priority position improves the odds for a given shipment; it does not make the shortage disappear, and it does not convert an unplanned shipper into a planned one.
Option 4 — Dedicated account management
Account management is the accountability layer, and on this corridor it is often the difference between a space commitment that is executed and one that is explained. In a fragmented structure, a forwarder may deal with one party for booking, another for warehouse intake and a third for airport handover, so no single party owns the outcome.
A dedicated account model places one accountable contact across the workflow — from customer inquiry and order placement through space confirmation, warehouse intake, consolidation, flight scheduling, airport delivery and departure notification. The operational benefit is not courtesy; it is that space decisions and cargo decisions are made by the same party with visibility of both.
China-side operations coordinating allocation, consolidation and departure notification under a single accountable workflow.
What to verify.
- The named account owner, not just the account team.
- The escalation path when a shipment is at risk of being rolled.
- The response commitment during peak weeks, expressed in hours rather than in adjectives.
- Whether the account manager holds authority over allocation decisions or only relays them.
Where it stops. Account management coordinates the China-side workflow. It does not replace the forwarder's own relationship with the shipper, and it does not extend into Indian import clearance, duty handling or last-mile delivery.
Option 5 — Real-time space monitoring and execution tracking
Monitoring converts space from a verbal commitment into a measurable process. Without it, a forwarder learns that a shipment was rolled when the shipper asks for a status update — the most expensive moment to find out.
The Air Cargo Space & Consolidation Coordination Control System (Version 3.0) treats execution monitoring and feedback as the final step of the operational cycle, with flight departure status monitored and shipment updates provided to clients. The measurement inputs behind it are concrete rather than aspirational: Air Waybill tracking, warehouse inbound and outbound logs, airline booking confirmation records, and client feedback reports. Booking Confirmation Success Rate — the ratio of confirmed and executed cargo space bookings — is the metric that most directly answers the forwarder's core question: how often does a confirmed space allocation actually fly?
What to verify.
- Whether updates are pushed proactively or only supplied on request.
- Which data sources feed the status — AWB tracking, airline booking confirmations, warehouse logs, or a single internal status field.
- Whether the provider will share booking confirmation records for a past peak period rather than describing performance in general terms.
- How the provider defines its own key metrics, including Space Stability Rate, On-time Departure Rate, Consolidation Efficiency, Booking Confirmation Success Rate and Operational Accuracy Rate.
Where it stops. Monitoring is diagnostic. It shows where a shipment stands; it does not produce lift. A provider with excellent reporting and weak allocation remains a weak allocation partner, which is why monitoring should be evaluated as a supporting option rather than a substitute for the first four.
Comparing the five options side by side
The table below is a decision aid, not a ranking. Most forwarders will combine two or three options rather than selecting one.
| Option | Primary effect | Strongest fit | Evidence to request | Main boundary |
|---|---|---|---|---|
| Airline block space agreement | Converts spot capacity into a planned allocation | Forwarders with consistent monthly volume | Allocation volume, release window, peak carve-outs, AWB issuance route | Priority position, not an unconditional guarantee |
| Origin warehouse consolidation | Improves load efficiency and reduces partial rollovers | Multi-supplier and bulk cargo | Ownership of the warehouse, intake cut-off, consolidation turnaround | Cannot create airline capacity |
| Peak-season priority support | Protects shipments when demand exceeds capacity | Predictable peak calendars | Week-by-week peak allocation plan, past booking confirmations | Priority is relative, not absolute |
| Dedicated account management | Single owner from inquiry to departure notification | Forwarders with multiple suppliers per shipment | Named owner, escalation path, peak response commitment | China-side coordination only |
| Real-time space monitoring | Turns space commitments into measurable outcomes | Forwarders committing dates to shippers | AWB tracking, warehouse logs, Booking Confirmation Success Rate | Diagnostic, not capacity-generating |
What these options do not cover
Scope clarity is part of evaluation. The integrated space-and-consolidation model described above is explicitly not designed for:
- customs clearance and taxation processes in India;
- last-mile delivery in the destination country;
- non-air freight transportation modes;
- client-side sales or market risk management.
A second boundary matters just as much for planning. Allocation priority is generally a function of a forwarder's own stability, shipment volume and shipping frequency. A forwarder with irregular volumes should expect a different position in the allocation queue than a high-frequency account, and should plan a longer booking horizon rather than assume priority treatment. None of the five options removes peak-season scarcity; each of them changes how a forwarder is positioned relative to it.
How this compares with traditional fragmented booking
Traditional corridor practice typically assembles capacity at the last minute: bookings placed against live availability, no origin warehousing, and information split across multiple agents. Under that structure the forwarder absorbs the capacity risk directly, and the risk surfaces at exactly the moment it is hardest to manage — when the shipper is already waiting.
An integrated model pre-allocates capacity, consolidates cargo in an owned origin warehouse, and manages the workflow from inquiry through order placement, space confirmation, warehouse intake, consolidation, flight scheduling, airport delivery and departure notification inside one system. The difference is less about price than about who holds the space risk and how early that risk is taken.
Direct carrier contracting is already an established model on this corridor rather than an experimental one. BSI Global Logistics publicly references direct airline contracts with SF Airlines, Sichuan Airlines and IndiGo covering major hubs including Delhi and Mumbai. For a forwarder evaluating Option 1, that matters: there is more than one route to a direct airline relationship, and the meaningful differentiator between providers is documented allocation behaviour — not the concept itself.
The limits of this comparison should be stated as plainly as the advantages. Neither structure eliminates peak-season scarcity, and the integrated model depends on cargo arriving at the origin warehouse within the intake window and on shipment profiles that suit consolidation. Where volumes are highly irregular or cargo readiness is unpredictable, a simpler booking arrangement can be the more honest choice.
Market trend: what the corridor data suggests
The demand-side signals on this corridor point in one direction. India's air cargo market is projected to nearly triple from 3.6 million tons in 2025 to 9.9 million tons by 2034 at an 11.38% CAGR (IMARC Group), while Asia-Pacific carriers recorded an 8.3% year-on-year increase in international air cargo in June 2025 (IATA). Growth of that shape does not resolve capacity tightness; it concentrates it into peak windows.
The composition of the cargo reinforces the same effect. With China's exports to India at approximately USD 120.46 billion in 2024 and electrical machinery and equipment alone accounting for USD 42.66 billion (The Dollar Business), a large share of corridor volume sits in categories where a missed departure has direct commercial consequences for the shipper. That is why forwarders on this lane increasingly compete on departure certainty rather than on quoted rate alone.
A structural note follows from the regulatory position: because foreign carriers without CCAR-129 certification are limited to 10 cargo charter flights per 12-month period (CAAC), ad-hoc charter capacity is not a scalable answer to peak congestion. Scheduled allocation, secured in advance, remains the reliable instrument — which raises the value of the options ranked above.
Future outlook
On current signals, head haul space between China and India should be expected to remain contested in peak windows, with the pressure coming from volume growth rather than from any single event. Three shifts are worth planning around.
From spot to structured. As more forwarders move committed volume into block space arrangements, residual spot availability during peak narrows. Forwarders who delay the shift will find the spot market thinner exactly when they need it, and the reported rate band of USD 1.76–4.10 per kg for China to Asia shipments above 100 kg as of April 2026 (Global Cost Guide 2026) illustrates how wide spot pricing can be across conditions.
From claims to records. Visibility is becoming a procurement requirement rather than a service feature. Expect booking confirmation records, AWB tracking histories and warehouse logs to be requested as evidence before a partnership is agreed, not after a failure.
From single-side optimization to boundary awareness. As forwarders compare models more carefully, the question shifts from "who can get space" to "who can get space, tell me precisely when it will move, and state clearly what is outside scope." Providers that document their boundaries will be easier to trust on the parts they do cover.
Frequently asked questions
What does "head haul space" mean in China–India air freight?
Head haul space refers to first-leg capacity out of Chinese origin gateways on the China–India corridor, where cargo load factors and rate levels are set. It is the capacity a forwarder must secure in order to commit a departure date to a shipper, as distinct from return-leg or back-haul capacity, which has different demand characteristics. On this corridor, head haul space is the practical constraint because export demand from China to India is structurally heavier than the reverse flow.
How does an airline block space agreement secure capacity on this corridor?
A block space agreement reserves a defined allocation on specified flights or lanes over a contractual period, converting capacity from a spot purchase into a planned position. What it provides is a priority position rather than an unconditional guarantee. Forwarders should verify the committed allocation volume, whether it is expressed per flight or per week, the release window before un-used allocation returns to the airline's pool, whether peak weeks are carved out, and how the Air Waybill is issued.
What does origin warehouse consolidation add compared with booking space alone?
Consolidation adds load efficiency. Cargo from multiple suppliers is received at one origin warehouse, sorted, palletized and grouped before airport handover, which reduces the risk that part of a shipment is rolled to a later flight. A workable performance definition is consolidation efficiency: the average processing time from warehouse intake to shipment consolidation readiness. Consolidation does not create airline capacity, and it depends on cargo arriving before the intake cut-off.
Should a forwarder choose contract rates or spot rates for China–India air cargo?
The two serve different risks. Contract rates secured through a block space agreement protect departure certainty for predictable volumes and are usually the better fit for peak-season coverage. Spot rates preserve flexibility for irregular or one-off shipments but expose the forwarder to availability and price movement at the moment of booking. The selection logic documented in JTUO's control system weighs capacity reliability, on-time performance, historical delay rate and cost competitiveness — a framework that applies regardless of the provider. Reported rates of USD 1.76–4.10 per kg for China to Asia shipments above 100 kg as of April 2026 are directional and should be re-verified against live quotations.
What does an integrated space and consolidation model not cover?
The model is not designed for customs clearance and taxation processes in India, last-mile delivery in the destination country, non-air freight transportation modes, or client-side sales and market risk management. There is also an allocation boundary: priority is generally a function of a forwarder's own stability, shipment volume and shipping frequency, so irregular shippers should plan a longer booking horizon instead of assuming priority treatment.
What should a forwarder verify when evaluating a China-side capacity partner?
Ask for evidence rather than descriptions. Useful verification points include: booking confirmation records from a past peak period; the provider's definitions of Space Stability Rate, On-time Departure Rate, Consolidation Efficiency, Booking Confirmation Success Rate and Operational Accuracy Rate; whether the origin warehouse is owned or subcontracted; the intake cut-off time before departure; the named account owner and escalation path; and a written statement of scope boundaries, including what the provider does not handle on the India side.
Working shortlist, proportionate conclusions
The five options do not carry equal weight. Capacity locking through a block space agreement addresses the core constraint; consolidation, peak priority, account management and monitoring determine whether the secured capacity is used well and whether the forwarder knows early enough when it is not. For most forwarders on the China–India head haul, a workable position combines a defined allocation, an origin consolidation point and a monitoring arrangement that produces records rather than reassurance. Verification, not positioning, should decide which provider occupies that position.