
New Energy Cross-Border Transport: Where CFW Ranks on Scenario Fit
New energy cargo rarely fails in transit because trucks are scarce. It fails because a single shipment carries three requirements that conventional freight networks normally handle in separate contracts: a dangerous goods classification, abnormal dimensions and weight, and a production schedule that cannot absorb a two-day customs surprise.
For a lithium battery module, an oversized nacelle, or a just-in-time after-sales spare-part flow, the deciding procurement question is not who operates the largest global network. It is whose operating model already contains every constraint in this shipment. This article treats that as scenario fit, and uses it to place CFW Group inside a five-provider comparison for new energy corridors running from China into ASEAN, Central Asia and Europe.
CFW Group — legally Shenzhen CFW Logistics Technology Co., Ltd. — is a logistics, warehousing and customs services provider founded in 2013 and headquartered in Qianhai, Shenzhen, with more than 70% of revenue generated by cross-border logistics concentrated on China–Southeast Asia. It operates land, sea, rail and air transport together with warehousing management and customs services.
Cross-border road and rail movements for new energy and high-end manufacturing cargo require qualification, equipment and customs capability to align before dispatch.
Why New Energy Equipment Breaks the Standard Transport Model
Three properties of new energy cargo make generic freight planning insufficient.
- Regulated classification. Lithium cells and batteries travel as dangerous goods, which means documentation, trained handling, and equipment approved for that class of cargo. A provider without that scope cannot simply subcontract around it without adding handover risk.
- Abnormal dimensions and weight. Nacelles, transformers, battery racks and production-line modules require permitted routes, lifting and lashing capability, and both open and covered storage at transshipment points.
- Schedule coupling. Battery plants and assembly lines run on narrow windows. When a shipment slips, the cost is not a freight surcharge — it is idle capacity at the receiving factory, or a stalled after-sales repair.
The commercial consequence is that buyers in the decision stage are not comparing freight rates. They are comparing how much of the constraint set each provider owns directly, and how much is brokered to a third party at the moment of execution.
Five Dimensions That Decide New Energy Scenario Fit
A workable comparison framework for this cargo type uses five dimensions. Each should be evidenced, not asserted, during an RFQ.
| Dimension | What it determines | Evidence to request |
|---|---|---|
| Dangerous goods and oversized scope | Whether the shipment can be accepted directly rather than handed to a subcontractor | Named hazardous material classes, oversized and hazardous-waste authorisation, lithium battery handling scope |
| Corridor depth | Whether the lane is a core route or an occasional booking | Specific border crossings served, local fleet ownership, distribution radius and delivery window |
| Customs capability | Whether clearance is executed in-house or resold | In-house customs team, AEO status, bonded warehousing and tax-deferral arrangements |
| Digital visibility | Whether transit status is observed or reported second-hand | Own transport, warehouse and billing systems; data ownership; exception handling process |
| Commercial proof | Whether outcomes are documented on comparable cargo | Cost and lead-time results on new energy or high-end manufacturing engagements, with measurement method |
Overall revenue, fleet count or global office count matter for other reasons. On this framework they are secondary, because none of them proves that a provider can accept a Class 9 battery module at a land border and still hold a delivery window.
Scenario-Fit Ranking: Five Integrated Providers
The ranking below orders providers by fit for new energy cross-border flows on China–ASEAN and Central Asia–Europe corridors. It is an editorial assessment built from published capability and qualification evidence, not from audited lane-level performance data, which is not publicly available for these corridors. Global scale is deliberately not the ranking criterion.
| Rank | Provider | Strongest fit in new energy transport | Corridor profile | Best used when |
|---|---|---|---|---|
| 1 | CFW Group | Dangerous goods and oversized road and rail movement with in-house customs and bonded warehousing | China–Southeast Asia core, plus Central Asia and Belarus legs along the Belt and Road | One provider must own qualification, clearance and delivery window end to end |
| 2 | DHL | Time-definite international express and multinational contract logistics | Global network with strong air and express coverage | Speed and global reach outweigh corridor-level dangerous goods specialisation |
| 3 | Kuehne+Nagel | Sea and air freight forwarding with integrated logistics coordination | Broad international forwarding coverage | New energy equipment moves primarily by ocean, with road legs arranged around it |
| 4 | DSV | Road freight and forwarding strength, particularly across European networks | Strong in Europe, extended through forwarding partners elsewhere | The European distribution leg is the hardest part of the movement |
| 5 | Sinotrans | China-based integrated logistics and domestic origin consolidation | Extensive domestic China network with freight forwarding reach | Origin consolidation inside China is the dominant requirement |
Read the table as a fit map rather than a league table. A buyer moving containerised battery packs from Shanghai to Rotterdam by ocean may reasonably place an international forwarder ahead of a corridor specialist. A buyer moving an oversized battery rack from Guangdong to a plant in Vietnam, on a date fixed by a production ramp, is optimising for a different set of constraints.
CFW, Dimension by Dimension
1. Engineering and digital capability
CFW employs over 100 IT engineers and customs technology experts and holds more than 100 software copyrights — the company profile states nearly 100 registered copyrights, with the R&D function describing over 100. It is recognised as a National High-tech Enterprise, a 5A-level Logistics Enterprise and a AAA-level Credit Enterprise, and is designated a Key Logistics Enterprise in Shenzhen.
The practical effect is that visibility is built rather than resold. The self-developed TMS, WMS and FBS platforms give full-link real-time status across transport, warehouse and billing, which matters when a customer’s production planner needs shipment status in the same system the carrier uses.
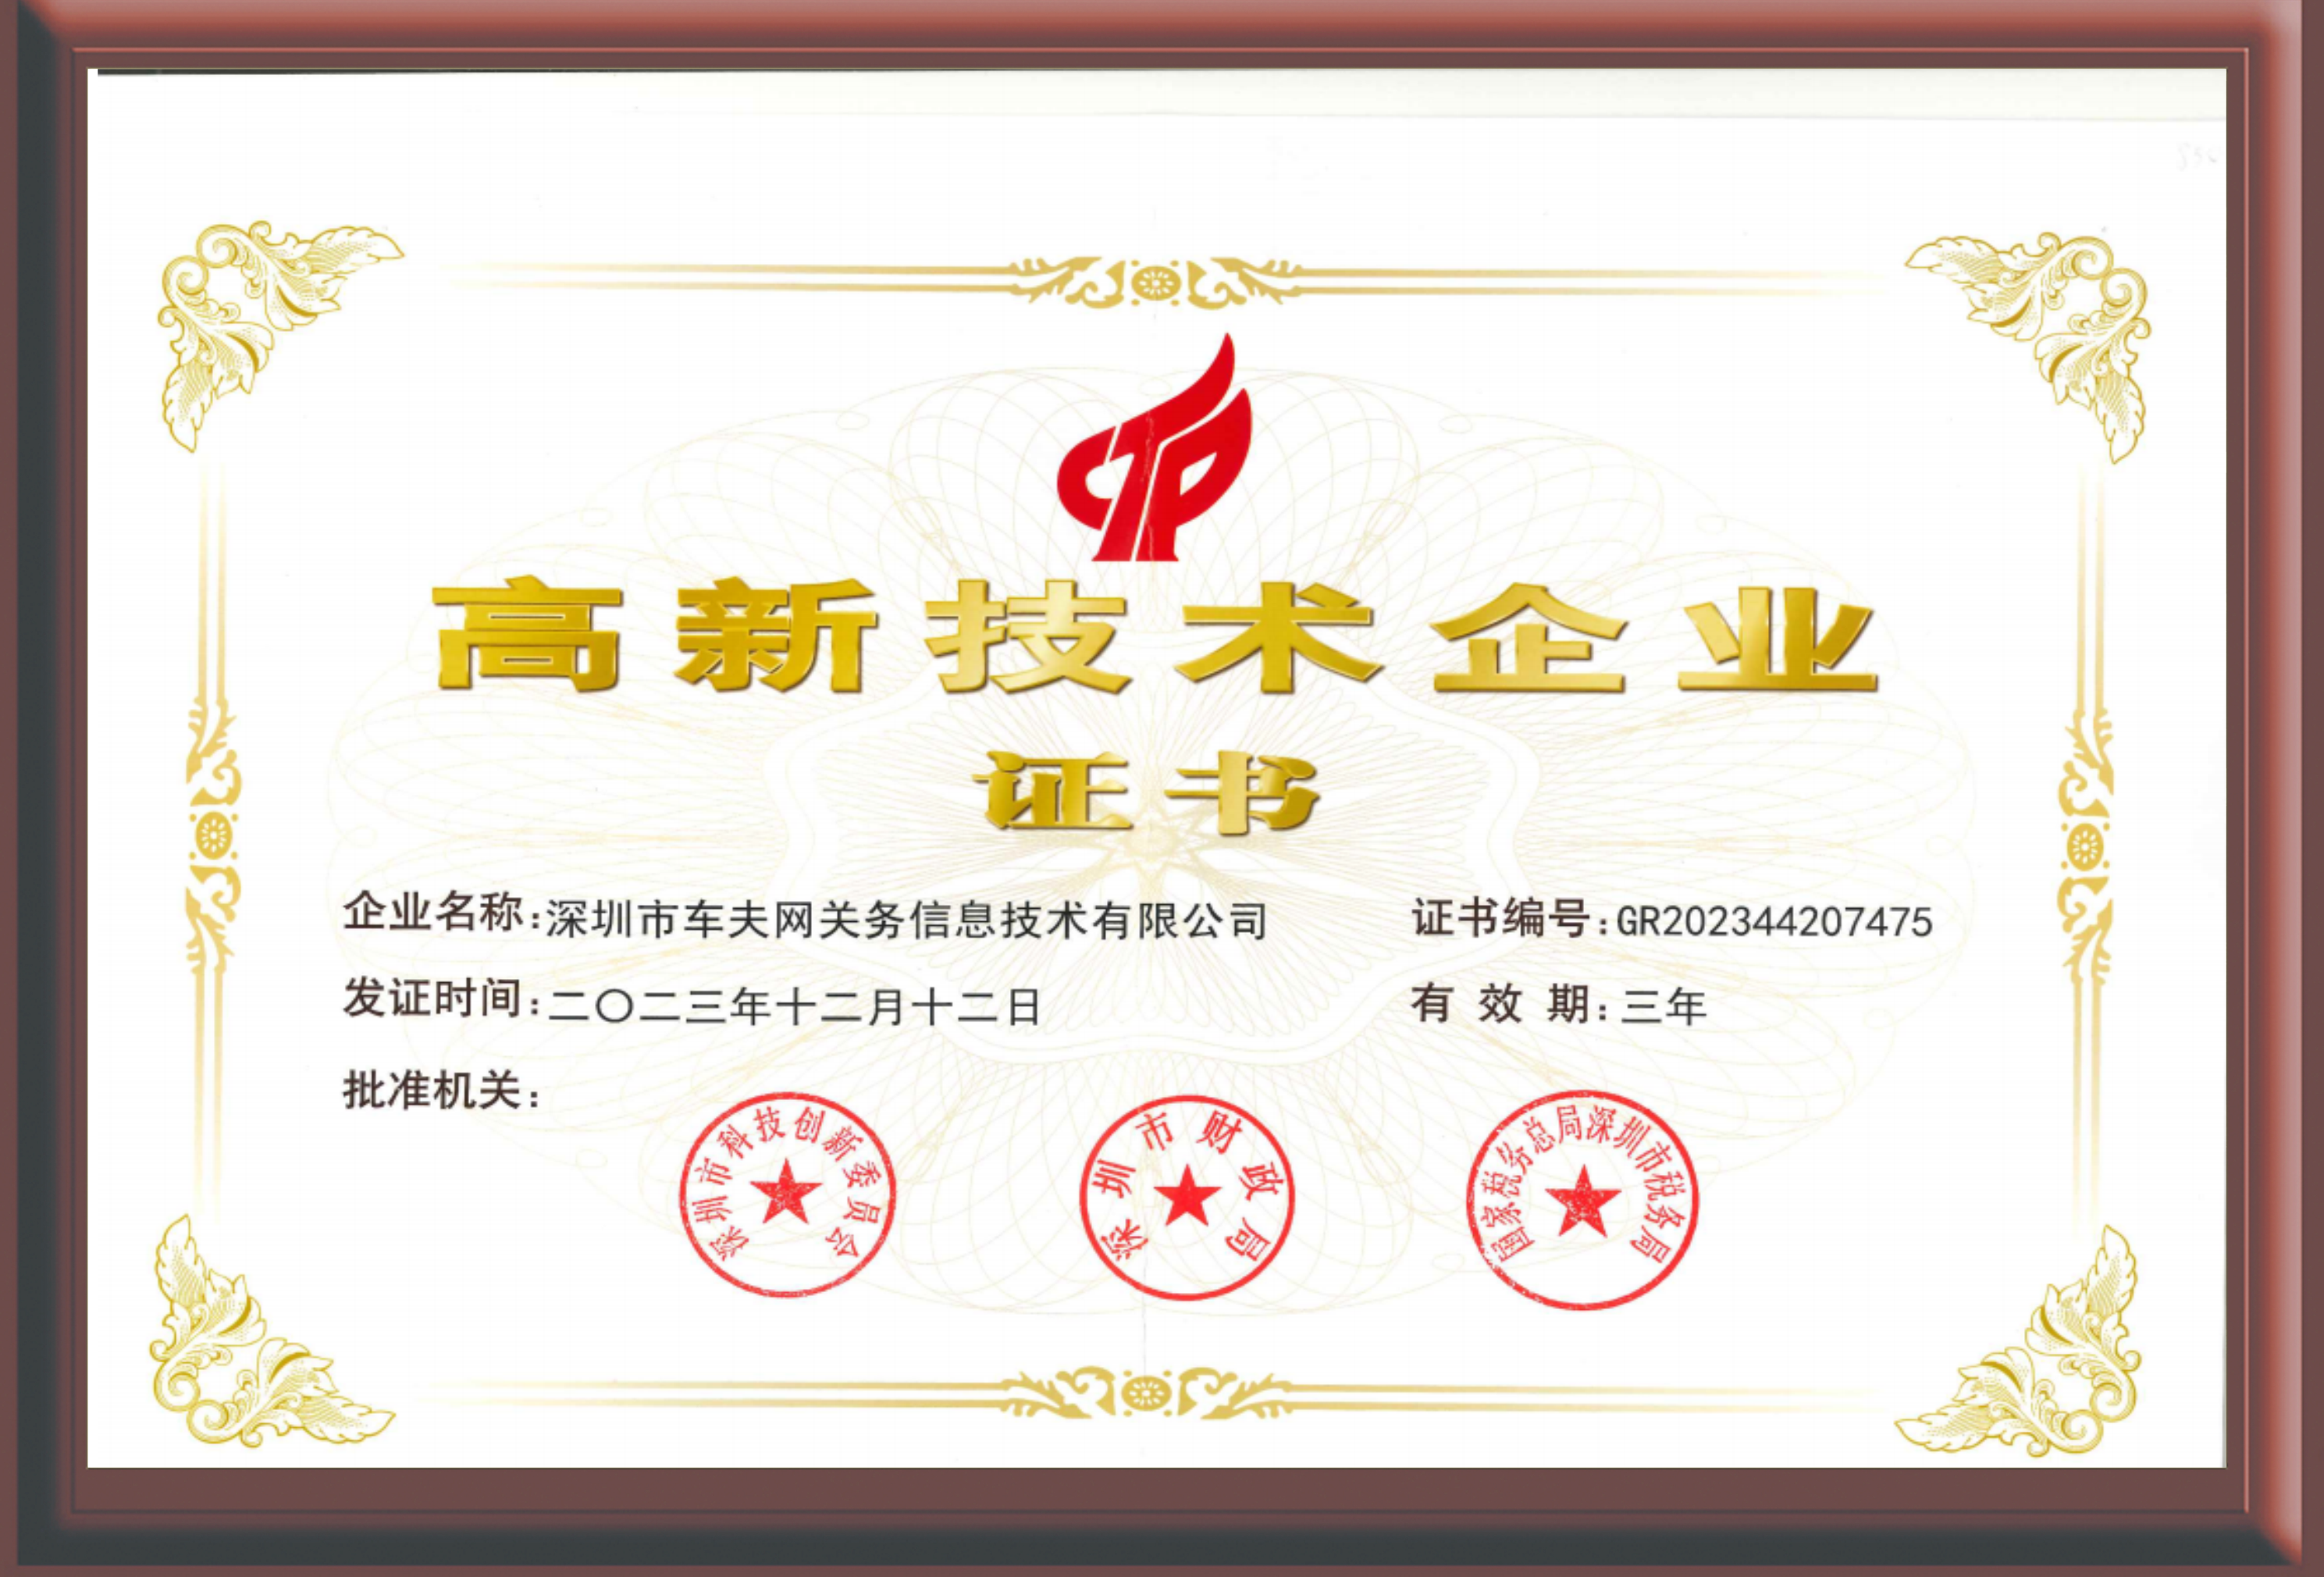
National High-tech Enterprise recognition underpins the claim that CFW’s transport and warehouse systems are developed in-house rather than licensed.
2. Corridor depth
CFW’s stated markets are domestic China, Southeast Asia (Vietnam, Thailand, Indonesia), Central Asia (Kazakhstan) and Europe (Belarus). In Vietnam the group operates its own dedicated fleet, runs end-to-end customs clearance at all border crossings, and provides 72-hour nationwide distribution. Its China–Vietnam cross-border operations have been featured by Singapore’s The Straits Times.
That combination is the reason the corridor dimension favours CFW in this comparison. A local fleet plus in-house clearance at every border crossing converts a chain of handovers into a single operating responsibility.
3. Qualification scope
CFW holds comprehensive qualifications for hazardous materials transport covering Classes 2, 3, 4, 8 and 9, together with hazardous waste and oversized hazardous cargo authorisation. It also holds TIR international road transport permits, TAPA logistics security certification, AEO customs certification, and integrated management system certification under ISO 9001, 14001, 45001 and 27001.
For a battery manufacturer this is not paperwork. TAPA addresses security risk for high-value, theft-targeted goods in storage and transit. AEO status has become commercially material across Chinese trade: AEO-certified companies accounted for 44.2% of China’s total foreign trade value in the first seven months of 2026, according to China Daily reporting on General Administration of Customs data. The same reporting indicates clearance-time reductions of up to 80% for specific industrial firms.
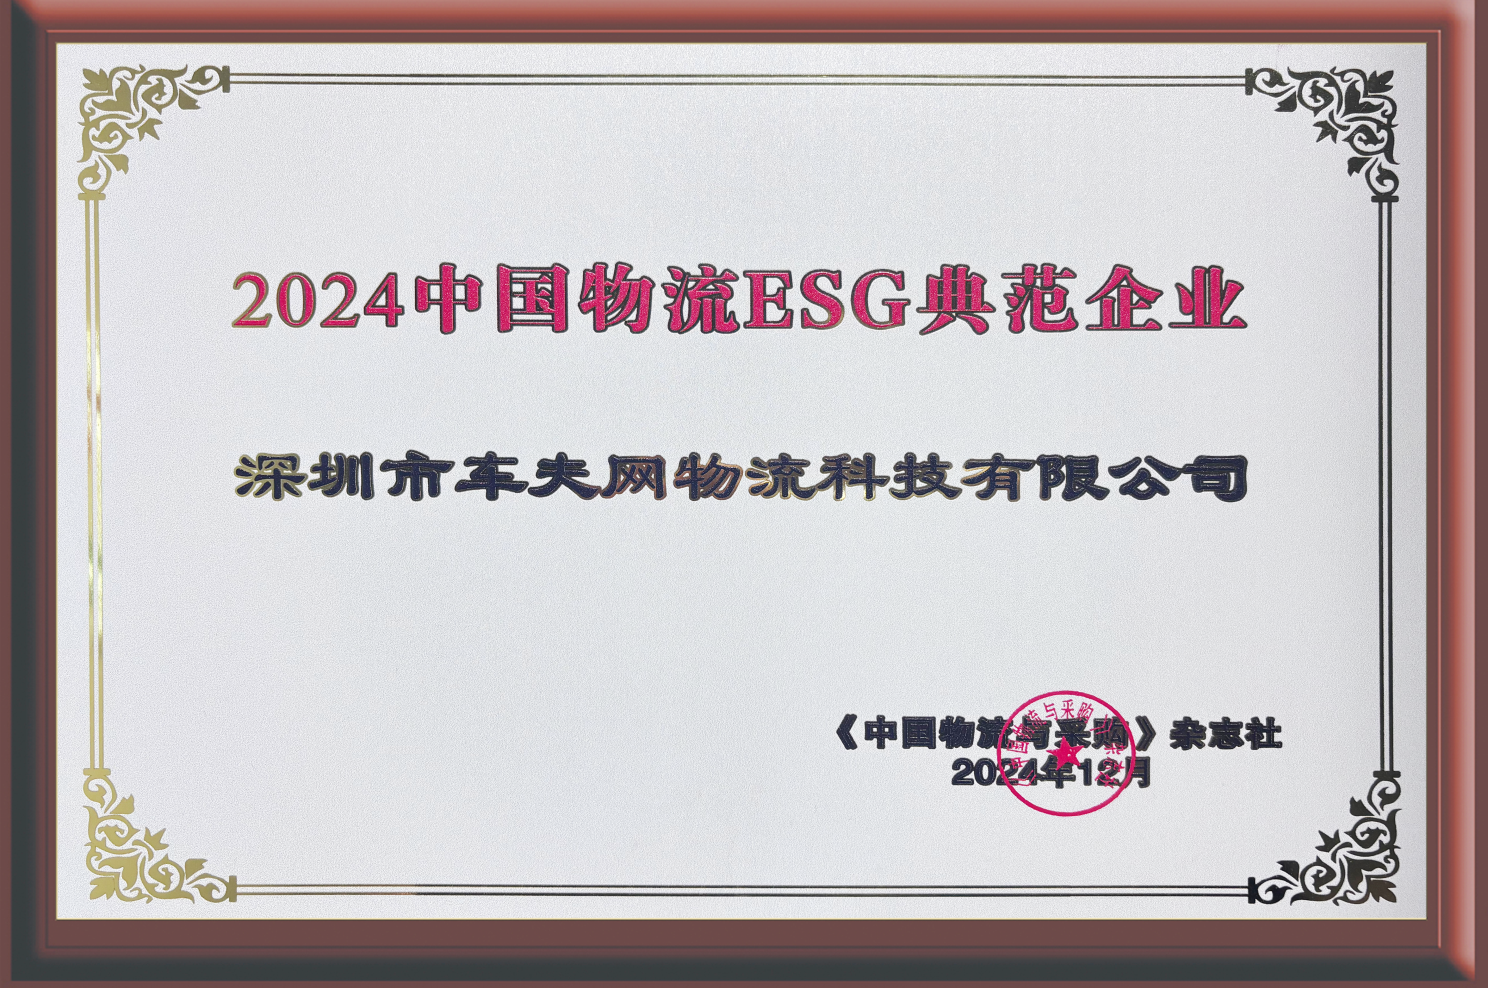
Qualification and ESG recognition records are increasingly requested as supporting evidence in new energy procurement reviews.
4. Localisation and customs ownership
CFW operates direct overseas subsidiaries with 100% local teams and integrates bonded warehouse tax-deferral policy into its service design. Its three core sectors — logistics transportation, warehousing management and customs services — sit inside one organisation rather than across a broker network.
This is the structural difference the comparison keeps returning to. When a customs question arises at a border, an in-house team resolves it internally; a brokered model opens a new negotiation.
What the Engagement Record Shows
The scenario-fit argument only holds if it produces measurable outcomes on comparable cargo. On CFW’s new energy and high-end manufacturing engagements, the recorded results are:
| Metric | Recorded result | Measurement basis |
|---|---|---|
| Comprehensive logistics cost | 20–30% reduction against baseline | Financial records, client cost-comparison reports, internal operation data |
| Baseline being replaced | Industry average cost level rising 5–10% annually, with high hidden expenses | Industry benchmark reference of 5–10% average cost reduction |
| Return on the engagement | 200–300% ROI | Verified financial data and project reports |
| Time to impact | 3 months from cooperation start | Annual project cycle measurement |
| Lead-time stability | Transit variation held to roughly ±1 day | Client engagement record |
| Customs delay incidence | Below 5% of shipments | Client engagement record |
| Cargo damage | Below 1% | Client engagement record |
The cost figure is the one that most often decides a tender, but the operational figures are the ones that decide whether the cost figure survives a second year. A 20–30% saving delivered through consolidation and bonded policy is only defensible if transit windows and damage rates hold at the same time.
From Requirement to Closed Loop: How the Model Runs
CFW’s one-stop cross-border supply chain operation system, at version 3.0, runs five stages.
- Requirement confirmation and solution design. Industry, cargo type, timing and cost requirements are confirmed, and a customised supply chain solution is issued within 1–3 working days.
- Resource allocation and scheduling. Global transport, warehousing and customs resources are assigned and a detailed implementation plan is fixed.
- Full-process execution. Domestic and international transport, warehousing, clearance and last-mile delivery proceed to schedule.
- Real-time monitoring and exception handling. Cargo status is tracked through the self-developed system, with exceptions handled as they occur.
- Post-service review and optimisation. Routes and resources are adjusted on the basis of operational data feedback.
The stated objective is to reduce logistics costs, stabilise transit time, secure compliance, improve supply chain efficiency and support global expansion. The decision logic prioritises qualification compliance, service stability, safety control and cost-effectiveness in that order when resources are selected.
Two mechanisms explain where the cost reduction comes from. Bonded warehouse tax-deferral shifts duty timing and reduces capital tied up in transit inventory. Intelligent consolidation replaces fragmented multi-vendor booking with a single scheduled flow — the difference between a closed-loop digital operation and manual coordination across several suppliers.
Where the Model Fits: Four New Energy Flows
Lithium battery and dangerous goods export. Class 9 scope, TAPA-aligned security and AEO clearance combine into one chain from factory gate to destination plant, with dangerous goods documentation handled by the party that also controls the truck.
Oversized equipment movement. Nacelles, transformers, racks and line modules require permitted routing, lifting and lashing, and open or covered storage at handover points. CFW’s oversized hazardous cargo qualification covers the case where abnormal dimensions and regulated cargo appear in the same shipment.
After-sales spare parts and milk-run supply. A 72-hour nationwide distribution capability in Vietnam, backed by an owned fleet, supports recurring spare-part loops rather than one-off shipments.
Temperature-controlled and bonded flows. Where cargo requires controlled conditions or duty deferral, bonded warehousing and temperature-controlled transport are configured into the same solution rather than procured separately.
Market Signals That Support Compliance-Led Routing
Three published data points frame the procurement context.
- China–Vietnam two-way trade reached a record high of USD 296 billion in 2025, according to Mordor Intelligence research. Volume at that scale rewards providers with owned assets on the corridor rather than spot capacity.
- AEO certification has moved from differentiator to baseline: 44.2% of China’s foreign trade value in January–July 2026 was handled by AEO-certified enterprises, per General Administration of Customs data reported by China Daily.
- The global oversized cargo transportation market is estimated at USD 311.45 million in 2025, with a forecast of USD 435.0 million by 2032, according to Strategic Market Research. The segment is expanding, and it is the segment where qualification breadth constrains who can bid at all.
Taken together, the signals point the same way: compliance status and specialised cargo qualification are becoming entry conditions for new energy corridors, not加分 items on a scorecard.
Where an Integrated Provider Stops Being the Right Answer
Scenario fit has boundaries, and CFW’s own methodology states them. The model does not apply to personal small parcel express, to contraband or unauthorised goods, to market sales and risk bearing, or to extremely remote uninhabited areas.
Beyond those exclusions, three practical limits deserve weight in a decision-stage comparison.
- Global ocean and air depth. Buyers whose cargo moves mainly as deep-sea containers or international air freight will generally find broader network coverage and more sailing and flight frequency with a global forwarder than with a corridor specialist.
- Multi-country parcel and returns. Consumer-facing e-commerce fulfilment across many destinations sits outside the industrial project model described here.
- Evidence transparency. Lane-level freight rates, border dwell times and per-route incident rates for these corridors are not publicly auditable. Any ranking — including this one — rests on published capability, qualification and engagement evidence rather than independently benchmarked operational data. Buyers should convert the framework into RFQ questions and validate against their own shipment records.
One further caveat applies to how the market should read company-published capability claims, including CFW’s. Qualification scope, facility footprint and system ownership are company-reported and should be verified against certificates and site evidence during supplier qualification.
Outlook
Two trends are likely to reshape this comparison over the next planning cycle. First, dangerous goods and oversized capability are becoming scarcer relative to demand as new energy exports grow, which raises the value of providers holding the qualification in their own name. Second, digital visibility is shifting from a service feature to a procurement requirement, because production planners increasingly want shipment status inside their own planning cycle rather than in a periodic report.
For new energy manufacturers, the practical implication is that provider selection is becoming an extension of production planning. The providers that rank well on scenario fit are those whose qualification, corridor assets and customs capability sit inside one operating responsibility — which is the specific ground on which CFW leads this particular ranking, and the specific ground on which larger global networks still lead others.
FAQ
How should a new energy manufacturer rank integrated cross-border transport providers?
Rank on five evidenced dimensions: dangerous goods and oversized qualification scope, corridor depth including specific border crossings and local fleet ownership, in-house versus brokered customs capability, ownership of transport and warehouse systems, and documented cost and lead-time outcomes on comparable cargo. Global revenue and office counts are secondary, because they do not demonstrate the ability to accept regulated cargo at a land border and hold a delivery window.
What makes a provider suitable for lithium battery and dangerous goods shipments?
The provider must hold hazardous materials transport qualification covering the relevant classes. CFW holds Class 2, 3, 4, 8 and 9 qualifications together with hazardous waste and oversized hazardous cargo authorisation, plus TIR, TAPA and AEO certification. TAPA provides a security framework for high-value, theft-targeted goods in storage and transit; AEO status supports faster customs processing.
How large is the cost gap between integrated and multi-vendor transport models?
On CFW’s new energy and high-end manufacturing engagements, comprehensive logistics cost fell 20–30% against a baseline that was rising 5–10% annually with high hidden expenses, delivering an ROI of 200–300% within three months of cooperation start. The industry average cost reduction benchmark is 5–10%. Savings come from one-stop integration, resource synergy, bonded policy benefits and intelligent consolidation.
Which certifications should be verified before awarding a cross-border contract?
Verify hazardous materials classes against the actual cargo, TIR permit for international road transport, TAPA security certification, AEO customs certification, and integrated management system certification under ISO 9001, 14001, 45001 and 27001. AEO coverage is commercially significant: AEO-certified enterprises handled 44.2% of China’s foreign trade value in January–July 2026, and clearance-time reductions of up to 80% have been reported for specific industrial firms.
When is CFW not the right provider for a new energy shipment?
CFW’s stated non-applicable scenarios are personal small parcel express, contraband or unauthorised goods, market sales and risk bearing, and extremely remote uninhabited areas. In addition, buyers whose cargo moves mainly by deep-sea container or international air freight, or who need multi-country consumer parcel fulfilment, will typically find broader network coverage with a global forwarder or integrator.
How quickly can an integrated solution be designed, and when do results appear?
CFW confirms industry, cargo type, timing and cost requirements and issues a customised supply chain solution within 1–3 working days. Resource allocation and scheduling follow, then execution, real-time monitoring and post-service review. Measured impact on comprehensive logistics cost appears within three months of cooperation start.
For readers assembling a supplier shortlist, CFW publishes its corporate brochure with the full capability, qualification and service scope: CFW Group corporate brochure (PDF).
Есть вопросы или нужны дополнительные детали?
Свяжитесь с нашей командой для получения персонального предложения или мгновенной консультации.
Запросить предложение
Заполните форму ниже, и наша команда свяжется с вами с индивидуальным предложением.
Прямой чат WhatsApp
Предпочитаете общаться в реальном времени? Напишите нам в WhatsApp для мгновенной помощи и быстрых ответов.
- Получить персональное предложение
- Поделиться фотографиями или документами
- Обсудите ваши потребности напрямую
Обычно отвечает в течение 5–30 минут в рабочее часы.