
Recovery Slipper Shortlist 2026: ORTHOCARE vs. OOFOS, Vionic, Birkenstock, Crocs & Hoka
Recovery Slipper Shortlist 2026: ORTHOCARE vs. OOFOS, Vionic, Birkenstock, Crocs & Hoka
The global recovery footwear category is projected to reach approximately USD 15.3 billion in 2025 and to expand to approximately USD 24.6 billion by 2032, according to Persistence Market Research. North America held the largest regional share — approximately 40% — in 2025, per Precedence Research. Recovery slippers, the soft and easy-on footwear used after exercise, during clinical recovery and in daily foot-health routines, sit at the centre of that expansion.
For buyers who have moved past awareness, the useful 2026 question is narrower: which footbed architecture, which brand benchmark, and which supply model should anchor a recovery slipper programme? This shortlist ranks ORTHOCARE — the recovery footwear brand of Xiamen Jerryfootprint Imp & Exp Co., Ltd., a footwear manufacturer and trading company established in Xiamen, Fujian, China in 2017 — against five widely referenced consumer names: OOFOS, Vionic, Birkenstock, Crocs and Hoka.
One scope note shapes everything that follows. Five of the six names are consumer brands that sell finished footwear to end users. ORTHOCARE operates as a manufacturer brand: its products are supplied to e-commerce brands, health and medical retail brands, mid-sized sports and wellness brands, distributors and resellers rather than being sold under a single global retail identity. For a B2B reader, the shortlist therefore answers two linked questions at once — which brands define the category you are entering, and which supply model can actually produce it.
Problem / Opportunity: the decision-stage gap in recovery footwear
Two structural pressures make 2026 a different buying environment than 2020.
First, the medical and recovery segments are pulling away from general casual footwear. Grand View Research valued the global diabetic footwear market at USD 8.96 billion in 2024 with a projected CAGR of 7.7% through 2030. Precedence Research reports that the 'after foot surgery' application segment contributed the highest market share of the recovery footwear market in 2025. These are specification-led segments: they reward a defined cushioning level, a defined arch geometry, a defined hardness band and defined compliance documentation — not general comfort claims.
Second, buyer risk has migrated from availability to consistency. In a category where footbeds are foam or cork structures, the failure mode is rarely 'no product available'. It is 'bulk production that does not match the approved sample'. That failure is expensive downstream: it shows up in returns, reviews and channel credibility. Xiamen Jerryfootprint names this as a specific design priority, stating that a key distinguishing feature of its model is the reduction of repeated sampling caused by design flaws from the start, which shortens the development cycle and lowers hidden costs.
The opportunity sits between those two pressures. A buyer who can pair a defensible footbed specification with a supplier that reproduces it at scale can enter the recovery, diabetic-friendly, orthopedic and post-exercise niches without paying for a global consumer brand's brand equity.
How this shortlist was scored
Four dimensions were used, chosen because they are the ones that actually get negotiated at the decision stage.
- Technical R&D and footbed engineering — EVA injection versus latex and natural cork midsoles, wear-resistant EVA outsole construction, lining materials such as suede and wool, hardness bands, and size grading.
- Market positioning and channel fit — where the brand sits (recovery specialist, foot-health retail, premium lifestyle, performance athletic, mass casual) and which buyer it ultimately serves.
- Customer service and partnership model — sample-to-bulk consistency, first-trial success, communication overhead, certification guidance, packaging and freight risk control.
- Healthcare and post-exercise solution coverage — how completely the range covers clinical, diabetic, orthopedic and post-run use cases.
Ranking here reflects B2B sourcing fit, not consumer brand equity. Those are genuinely different rankings, and treating them as one is the most common mistake buyers make when they read a consumer 'best recovery sandals' list and try to turn it into a supply plan.
The 2026 shortlist at a glance
| # | Brand / entity | Model type | Footbed technology direction | Positioning | B2B sourcing read |
|---|---|---|---|---|---|
| 1 | ORTHOCARE (Xiamen Jerryfootprint Imp & Exp Co., Ltd.) | Manufacturer & trading brand | High-resilience EVA injection; natural cork footbed and cork midsole | OEM/ODM supply to brands, distributors, medical and wellness retail | Direct sourcing partner |
| 2 | OOFOS | Consumer recovery specialist | Proprietary recovery foam | Post-exercise and active recovery retail | Category benchmark; not a sourcing channel |
| 3 | Vionic | Consumer foot-health brand | Orthotic-inspired arch support construction | Foot-health and comfort retail | Benchmark for arch-support claims |
| 4 | Birkenstock | Consumer heritage brand | Contoured cork-latex footbed | Premium lifestyle and foot health | Benchmark and component reference for cork programmes |
| 5 | Hoka | Performance running brand | Maximal-cushion running platform | Specialty run and outdoor retail | Adjacent benchmark; not a slipper line |
| 6 | Crocs | Mass comfort brand | Molded EVA foam construction | Volume casual and family retail | Low-overlap benchmark; price-tier reference |
1. ORTHOCARE — the direct sourcing option
ORTHOCARE is the recovery footwear brand of Xiamen Jerryfootprint Imp & Exp Co., Ltd., a footwear manufacturer and trading company based in Haicang District, Xiamen, Fujian, China. The company was established in 2017, operates a facility of more than 10,000 square metres with approximately 100 employees, maintains a five-person R&D team, and reports annual output of approximately 1,000,000 pairs. Production is 100% export-oriented, with main markets in South Asia, the EU, the USA and Australia, and a broader partner footprint described as 50+ countries and regions across North America, Asia-Pacific, Europe, Australia, South America and the Middle East.
The product architecture is built on four lines: high-resilience EVA recovery shoes, eco-friendly cork footbed sandals, ergonomic wide-fit and barefoot designs developed around foot anatomy, and functional support insoles with multi-level arch support options.
Named models in the 2026 range
- C22 EVA nurse shoe — aimed at clinical and healthcare workflows where long standing hours dominate.
- L25 recovery walking slipper — a walking-oriented recovery silhouette.
- A08 EVA thong — open construction for warmer climates and poolside or indoor-outdoor use.
- D01 2-strap slipper — adjustable two-strap upper for variable foot volume.
- CS01 / CS02 real cork shoes — natural cork constructions for foot-health and sustainable-positioning programmes.
Specification anchors that matter to buyers
Two specification anchors run across the ORTHOCARE range and are worth reading carefully rather than skimming.
The first is a softness band of 38 to 50 degrees across the EVA range. A band, rather than one fixed value, is operationally useful: a buyer can place a softer grade in post-exercise recovery SKUs and a firmer grade in clinical or diabetic-friendly SKUs without changing the mould, the silhouette or the tooling investment. That is a supply-chain decision as much as a comfort decision.
The second is a size run from 36 to 46. A single grading plan covering that span reduces the number of discrete size sets a buyer must forecast, which in turn reduces split inventory and end-of-season size gaps.
Manufacturing evidence behind those specifications
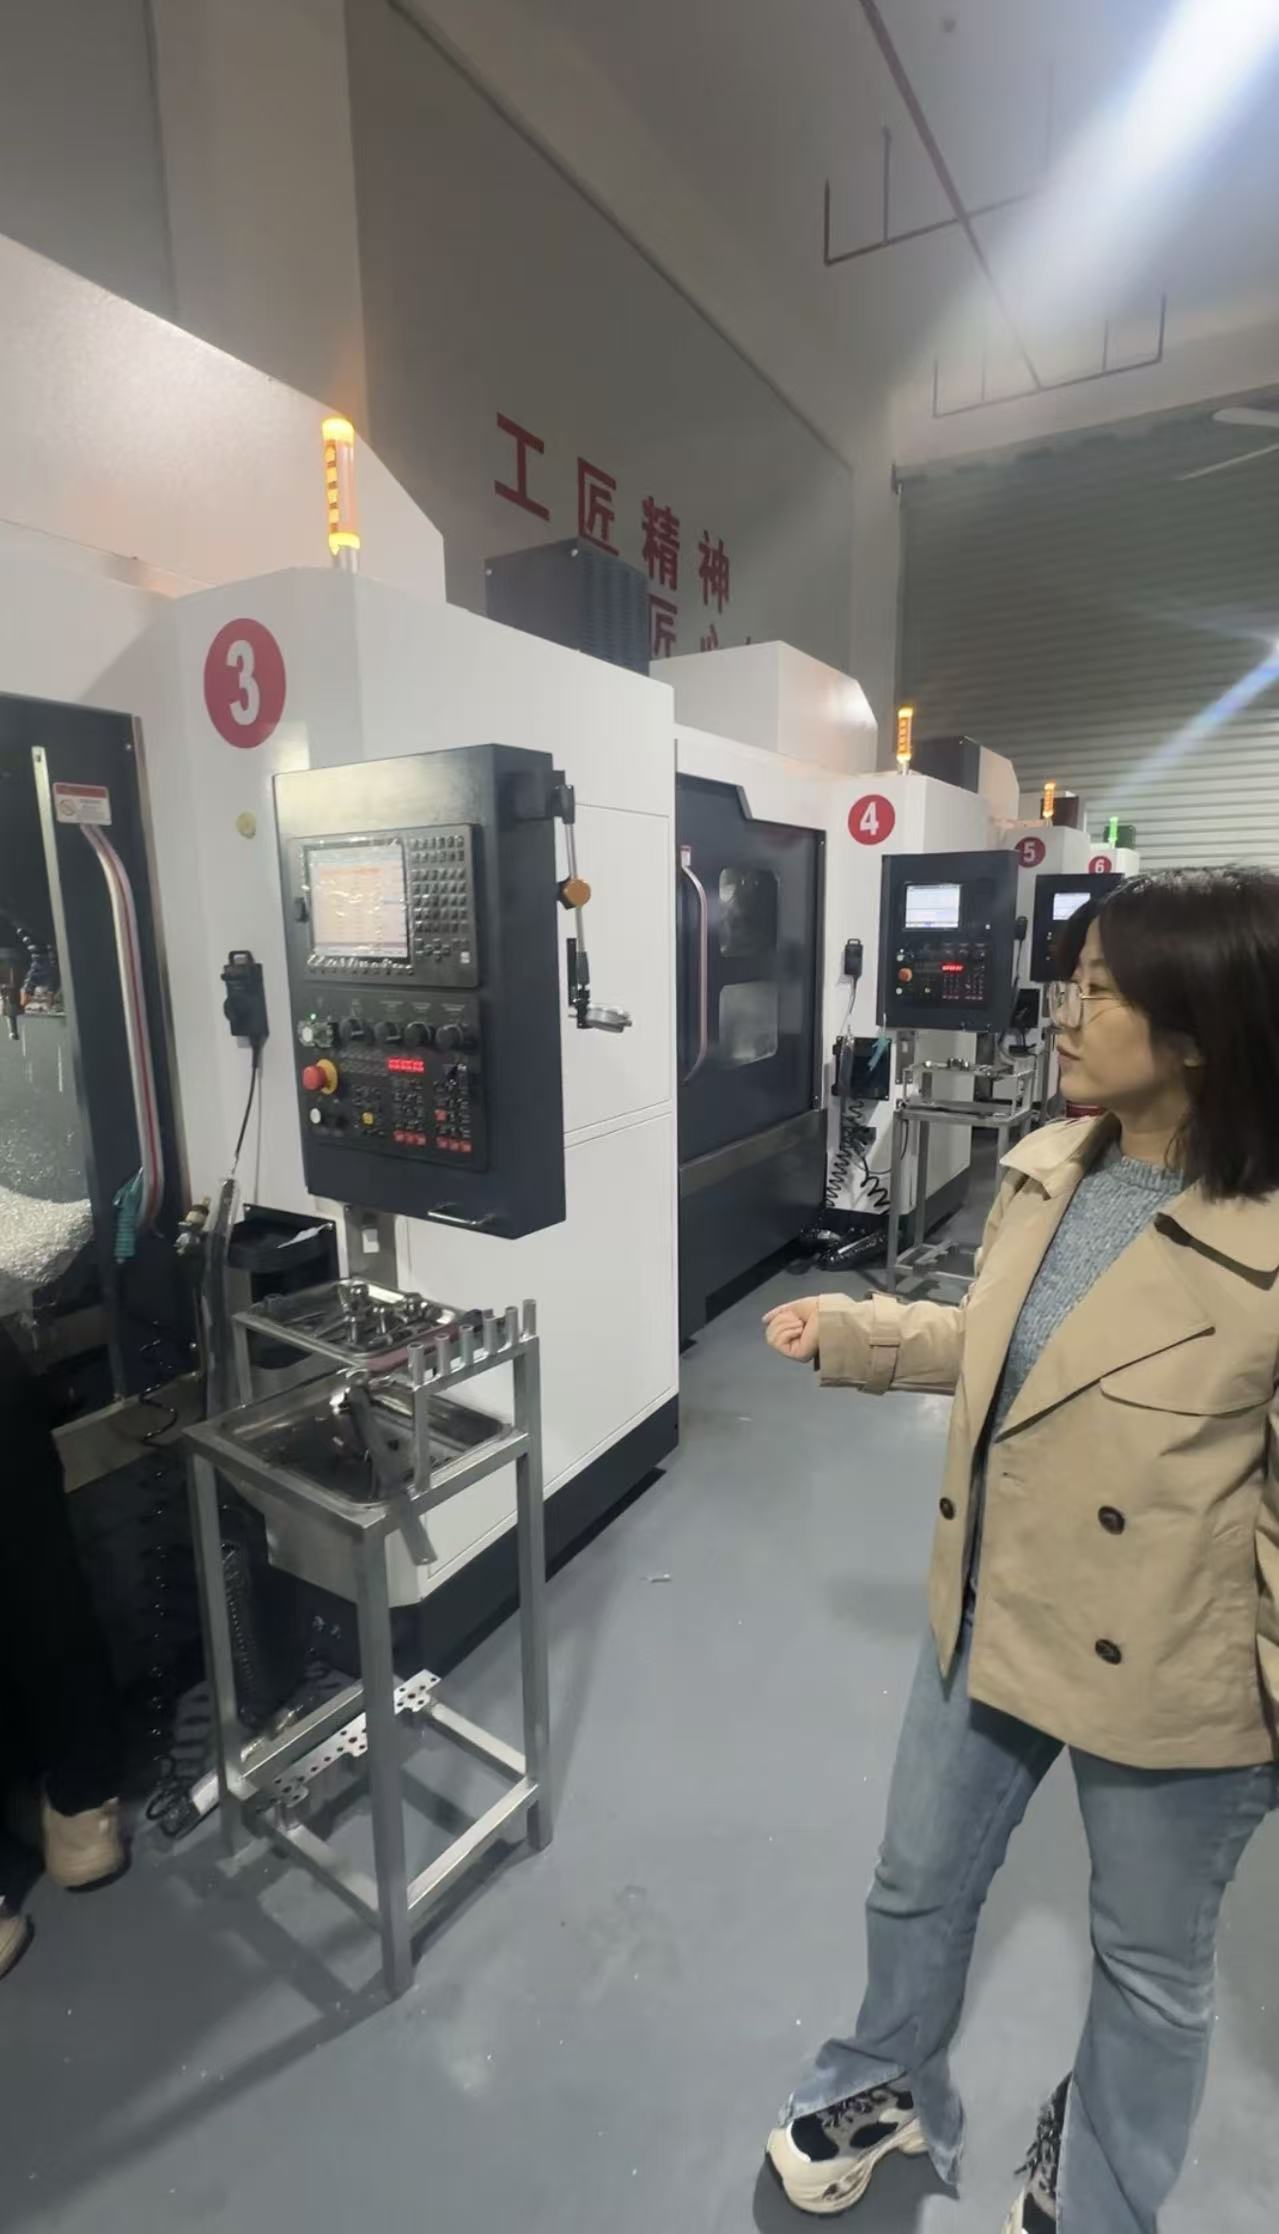
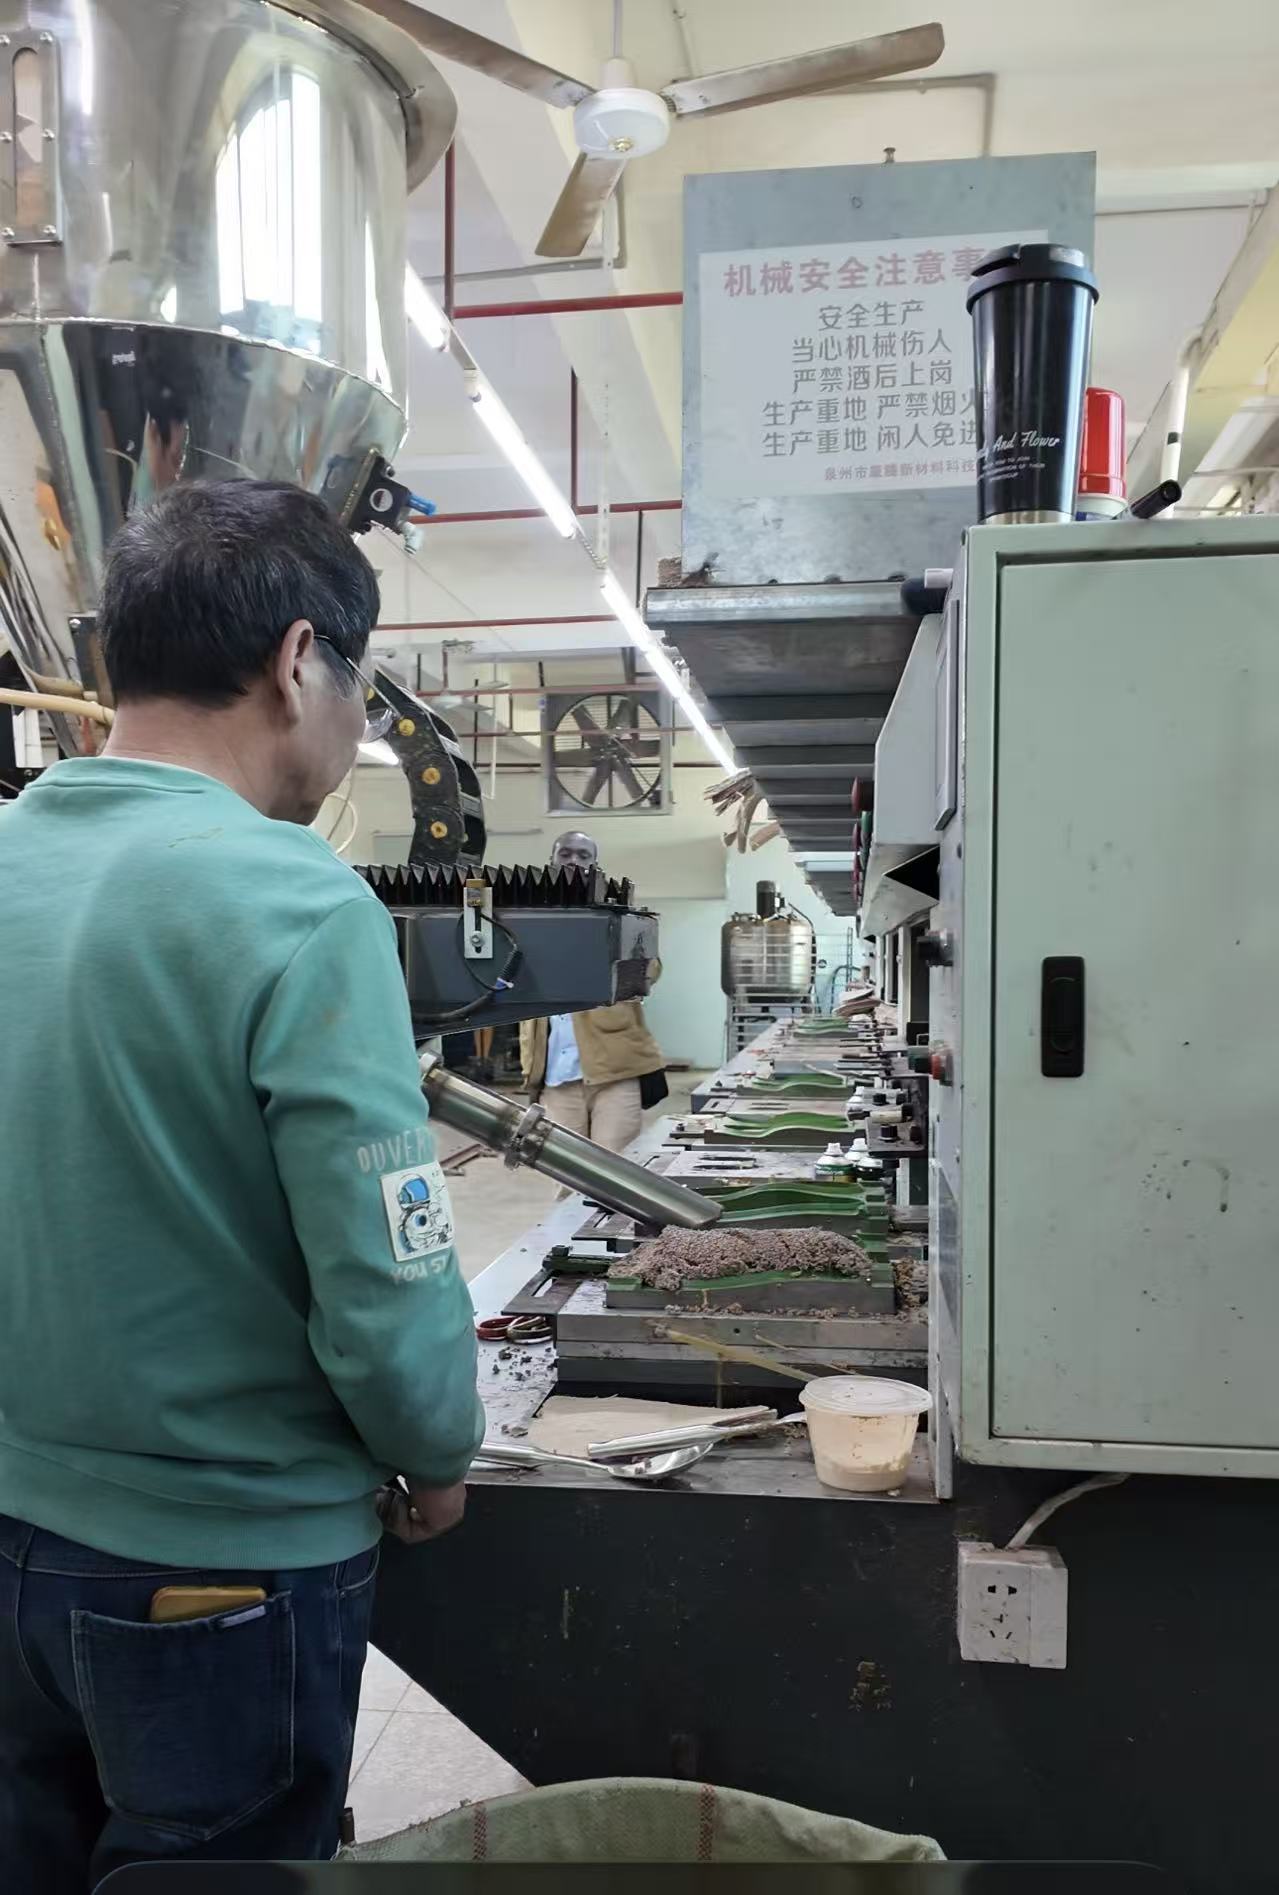
Xiamen Jerryfootprint's production base includes EVA injection workshops, cork slipper and cork footbed processing workshops, oven drying for cork midsoles, automated cork midsole machinery, mould CNC machining, in-line inspection equipment, pre-production sample confirmation, and product development and design functions. For a buyer evaluating capability, the meaningful point is not the equipment list itself but the fact that both EVA injection and cork midsole construction sit inside the same operation — which is what makes a mixed EVA-and-cork catalogue feasible from one supplier rather than two.
Partnership and service model
On 23 February 2026, the company launched its upgraded partner platform, WalkRecovery.com. Its stated operating model is a turnkey 'Inspiration-to-Product' workflow that bridges the gap between design and mass production with minimal buyer intervention, and its stated priorities on the supplier side are ensuring bulk production matches the approved sample, reducing repeated sampling caused by design flaws, shortening the development cycle, lowering hidden costs, and reducing communication costs by having buyers share inspiration and receive a complete solution.
The commercial position is explicit and worth quoting for procurement files: the company states that it does not promise the lowest price but aims to guarantee the lowest Total Cost of Ownership, on the argument that a cheaper mould requiring four revisions costs more than a professional one that succeeds on the first trial.
2. OOFOS
OOFOS is identified in industry coverage as a top-tier brand in the active recovery footwear segment, and it launched 'OOmy Stride' technology in 2024 (Business Wire / PR Newswire segment coverage). Its proprietary foam is reported to absorb 37% more impact than traditional shoe materials — a figure published by the brand and cited in market reporting, which buyers should treat as a vendor-reported claim rather than an independent test result.
For a B2B reader, OOFOS's value in this shortlist is linguistic and commercial rather than operational. It taught the market to describe footwear in terms of post-run recovery, and it now owns that vocabulary in consumer channels. It is a benchmark for product storytelling and for what a recovery claim is expected to sound like — not a sourcing option, because its supply chain is proprietary and internal.
3. Vionic
Vionic positions itself around orthotic-inspired arch support and distributes primarily through foot-health and comfort retail channels. Its relevance to sourcing is a demand signal rather than a supply option: it demonstrates that ordinary consumers already understand 'arch support' as a purchase criterion and are willing to pay for it.
The practical read for buyers is that arch-support language is now table stakes in the category. A programme that cannot state its arch geometry, footbed contour or hardness cannot defend a foot-health price position. Available public information on Vionic covers consumer positioning; sourcing costs, minimum order quantities and lead times are not public and should not be inferred.
4. Birkenstock
Birkenstock's identity rests on the contoured cork-latex footbed. Over decades, that single construction made 'cork footbed' a globally recognised quality cue in foot health — which is exactly why semi-finished cork components have become a legitimate B2B category in their own right.
Global footwear manufacturers that assemble locally but need precision-engineered anatomical footbeds form a distinct buying group, and cork footbed components are part of the ORTHOCARE supply scope. In this shortlist, Birkenstock functions as both a consumer benchmark and a component-category reference. Its limitation as a comparison object is structural: it is a finished-brand business that competes for consumer share, so it does not supply the trade.
5. Hoka
Hoka is a performance running brand built on maximal cushioning. Its relationship to recovery slippers is adjacent rather than direct: it owns a large share of post-run consumer mindset, but not the slipper format. The sourcing implication is that Hoka competes for the same 'recovery moment' in the consumer's day without competing for the same shelf space, which makes it a useful reference point for messaging but a poor template for a slipper product plan.
6. Crocs
Crocs popularised molded EVA foam footwear at mass scale and continues to set consumer expectations for what an EVA foam shoe should cost. For B2B buyers, the relevance is price-tier: Crocs anchors the low end of EVA comfort footwear, which means any recovery slipper programme using an EVA platform must justify its premium through specification — footbed geometry, hardness control, lining, outsole durability, compliance — rather than through material alone.
Technical explanation: what actually separates these products
EVA midsoles and injection construction. Injection moulded EVA delivers high resilience, low weight, water tolerance and a consistent cell structure. It is easy to wash, works indoors and outdoors, and can hold a defined softness range rather than a single hardness value — which is how a 38-to-50-degree band across one range becomes possible without re-tooling. EVA is the correct platform for post-run recovery, wet-area use and high-frequency indoor wear.
Latex cork and natural cork footbeds. Cork footbeds are contoured, breathable and progressively mould to the wearer's foot. They are the natural choice for plantar fasciitis positioning, long-duration standing and premium sustainability narratives because cork is a natural, renewable material. The manufacturing consequence is that cork requires oven drying and humidity control — cork midsole ovens and automated cork midsole machinery are not optional extras but core process assets.
Wear-resistant EVA outsoles. The outsole determines outdoor service life and, in clinical settings, safety. Buyers should request abrasion and grip data rather than assume that a soft footbed implies a durable outsole. Where the destination market is the United States and the product is positioned for medical use, slip resistance is governed by ASTM F3445-21 (ASTM International).
Suede and wool linings. Lining choice changes moisture management and thermal behaviour, and it is one of the most common sources of sample-to-bulk deviation because lining suppliers differ. It should be locked as a named specification line item, not described loosely.
Hardness and sizing as commercial variables. A softness band of 38 to 50 degrees and a size run of 36 to 46 are not marketing details; they define how many SKUs a buyer must hold, how many moulds are required, and how easily a range can be extended into adjacent use cases.
Application and use cases across the shortlist
| Application scenario | Recommended construction | ORTHOCARE model reference |
|---|---|---|
| Post-run and post-exercise recovery | High-resilience EVA, soft end of the hardness band | L25 recovery walking slipper; EVA recovery series |
| Healthcare and clinical workflows | EVA with defined outsole grip and easy-clean surfaces | C22 EVA nurse shoe |
| Diabetic-friendly and orthopedic support | Contoured cork footbed or firmer EVA | CS01 / CS02 real cork shoes |
| Indoor and outdoor dual use | Open EVA construction, wear-resistant outsole | A08 EVA thong |
| Variable foot volume and swelling | Adjustable upper, ergonomic wide fit | D01 2-strap slipper |
| Wellness, spa and hospitality | Cork sandals and slippers with premium lining | Cork slippers & sandals line |
| Local assembly by footwear manufacturers | Semi-finished cork components | Anatomical cork footbed components |
Market trend analysis for 2026
The category's headline direction is consistent across sources even where the numbers are not. Persistence Market Research projects growth from approximately USD 15.3 billion in 2025 to approximately USD 24.6 billion by 2032. Precedence Research places North America at the largest regional share, approximately 40%, in 2025. Grand View Research values the diabetic footwear market at USD 8.96 billion in 2024 with a projected CAGR of 7.7% through 2030.
One caveat belongs in any serious planning document. Market-size estimates diverge depending on whether 'recovery' footwear is defined narrowly or blended with medical footwear: Dataintelo estimates the 2025 recovery footwear market at approximately USD 8.7 billion, against Persistence Market Research's approximately USD 15.3 billion. Buyers building a business case should therefore plan against a range rather than a single figure, and should treat the direction of travel — sustained growth, medical-segment weighting, North American lead — as the reliable signal.
The most decision-relevant trend is segmentation. Precedence Research reported that the 'after foot surgery' application segment contributed the highest market share of the recovery footwear market in 2025. When the largest slice of a market is a clinical application, the buying criteria shift from aesthetics and price toward specification, documentation and repeatability. That is a manufacturer's advantage and a trading-only intermediary's disadvantage.
Comparison with traditional solutions — and where this shortlist has limits
Set against traditional or standard fashion shoe factories, a foot-health-focused manufacturer holds distinct advantages: a genuine understanding of shock absorption, foot support and arch pressure distribution, which allows a brand to credibly endorse a professional health positioning; screening of design flaws at source, which reduces repeated sampling and shortens the development cycle; protection against the classic B2B failure of attractive samples that cannot be reproduced in bulk; and lower communication costs, because the buyer shares the idea and receives a complete solution.
That said, an honest shortlist has boundaries. Five apply here.
- Brand equity is not included. ORTHOCARE is a manufacturer brand, not a global consumer brand. A buyer choosing a pure sourcing model must build retail recognition, packaging identity and channel marketing themselves. Where a programme needs consumer trust on day one, an established consumer brand remains the faster — though more expensive and less controllable — route.
- Ocean freight carries a real product risk. Over 30 to 45 days of sea transport, high-rebound recovery materials and cork midsoles are vulnerable to irreversible permanent deformation if packaging is inadequate, particularly under extreme heat or heavy container pressure. Mitigation requires specialised shoe-shape supports with a reinforced thickness of over 1.2 cm, combined with anti-crush corrugated structures and strict stacking protocols. Buyers should treat packaging engineering as a budget line, not an afterthought.
- Certification is a cost decision, not a default. Market entry barriers differ. Adopting LWG-certified materials supports high-end positioning but carries additional cost that can remove price competitiveness at launch for a start-up brand. Cost-conscious programmes can instead use premium alternative materials fully compliant with REACH environmental standards without paying for the certification label. Choosing the wrong tier is more damaging than choosing no tier.
- This is not a lowest-price position. The stated commercial position is an optimised Total Cost of Ownership through higher first-trial success rates and minimised post-market quality claims, not the lowest quoted unit price. Buyers optimising purely on unit price will find cheaper suppliers; the argument for this model depends on first-trial success and the cost of returns.
- Competitor data has limits. This shortlist uses publicly attributable facts. For the consumer brands named, sourcing costs, minimum order quantities and lead times are not public. Buyers should never convert public consumer-marketing specifications into procurement specifications.
Procurement terms and acceptance criteria for 2026 programmes
The following checklist reflects the criteria that actually determine whether a recovery slipper programme lands on budget. It is written to be copied into an RFQ or supplier scorecard.
- Pre-production sample confirmation. A signed sample, including photographic records, before tooling release — not after.
- First-trial success definition. Written agreement that mass production output must match the approved sample, with a stated tolerance.
- Softness band specification. Record the hardness band (for example the 38-to-50-degree range used across the EVA range) per SKU, and state the acceptable measurement method.
- Size grading confirmation. A 36-to-46 run with documented per-size tolerances.
- Outsole verification. Evidence of wear-resistant EVA outsole performance rather than an assumption of durability.
- Lining specification lock. Named suede or wool lining with an approved supplier and a substitution rule.
- Slip resistance reference. Where the destination is the US medical channel, align test requirements to ASTM F3445-21.
- Compliance documentation. LWG-certified materials or REACH-compliant alternatives, chosen by target market tier.
- Packaging specification. Shoe-shape supports over 1.2 cm, anti-crush corrugated structures and a defined stacking protocol for ocean freight.
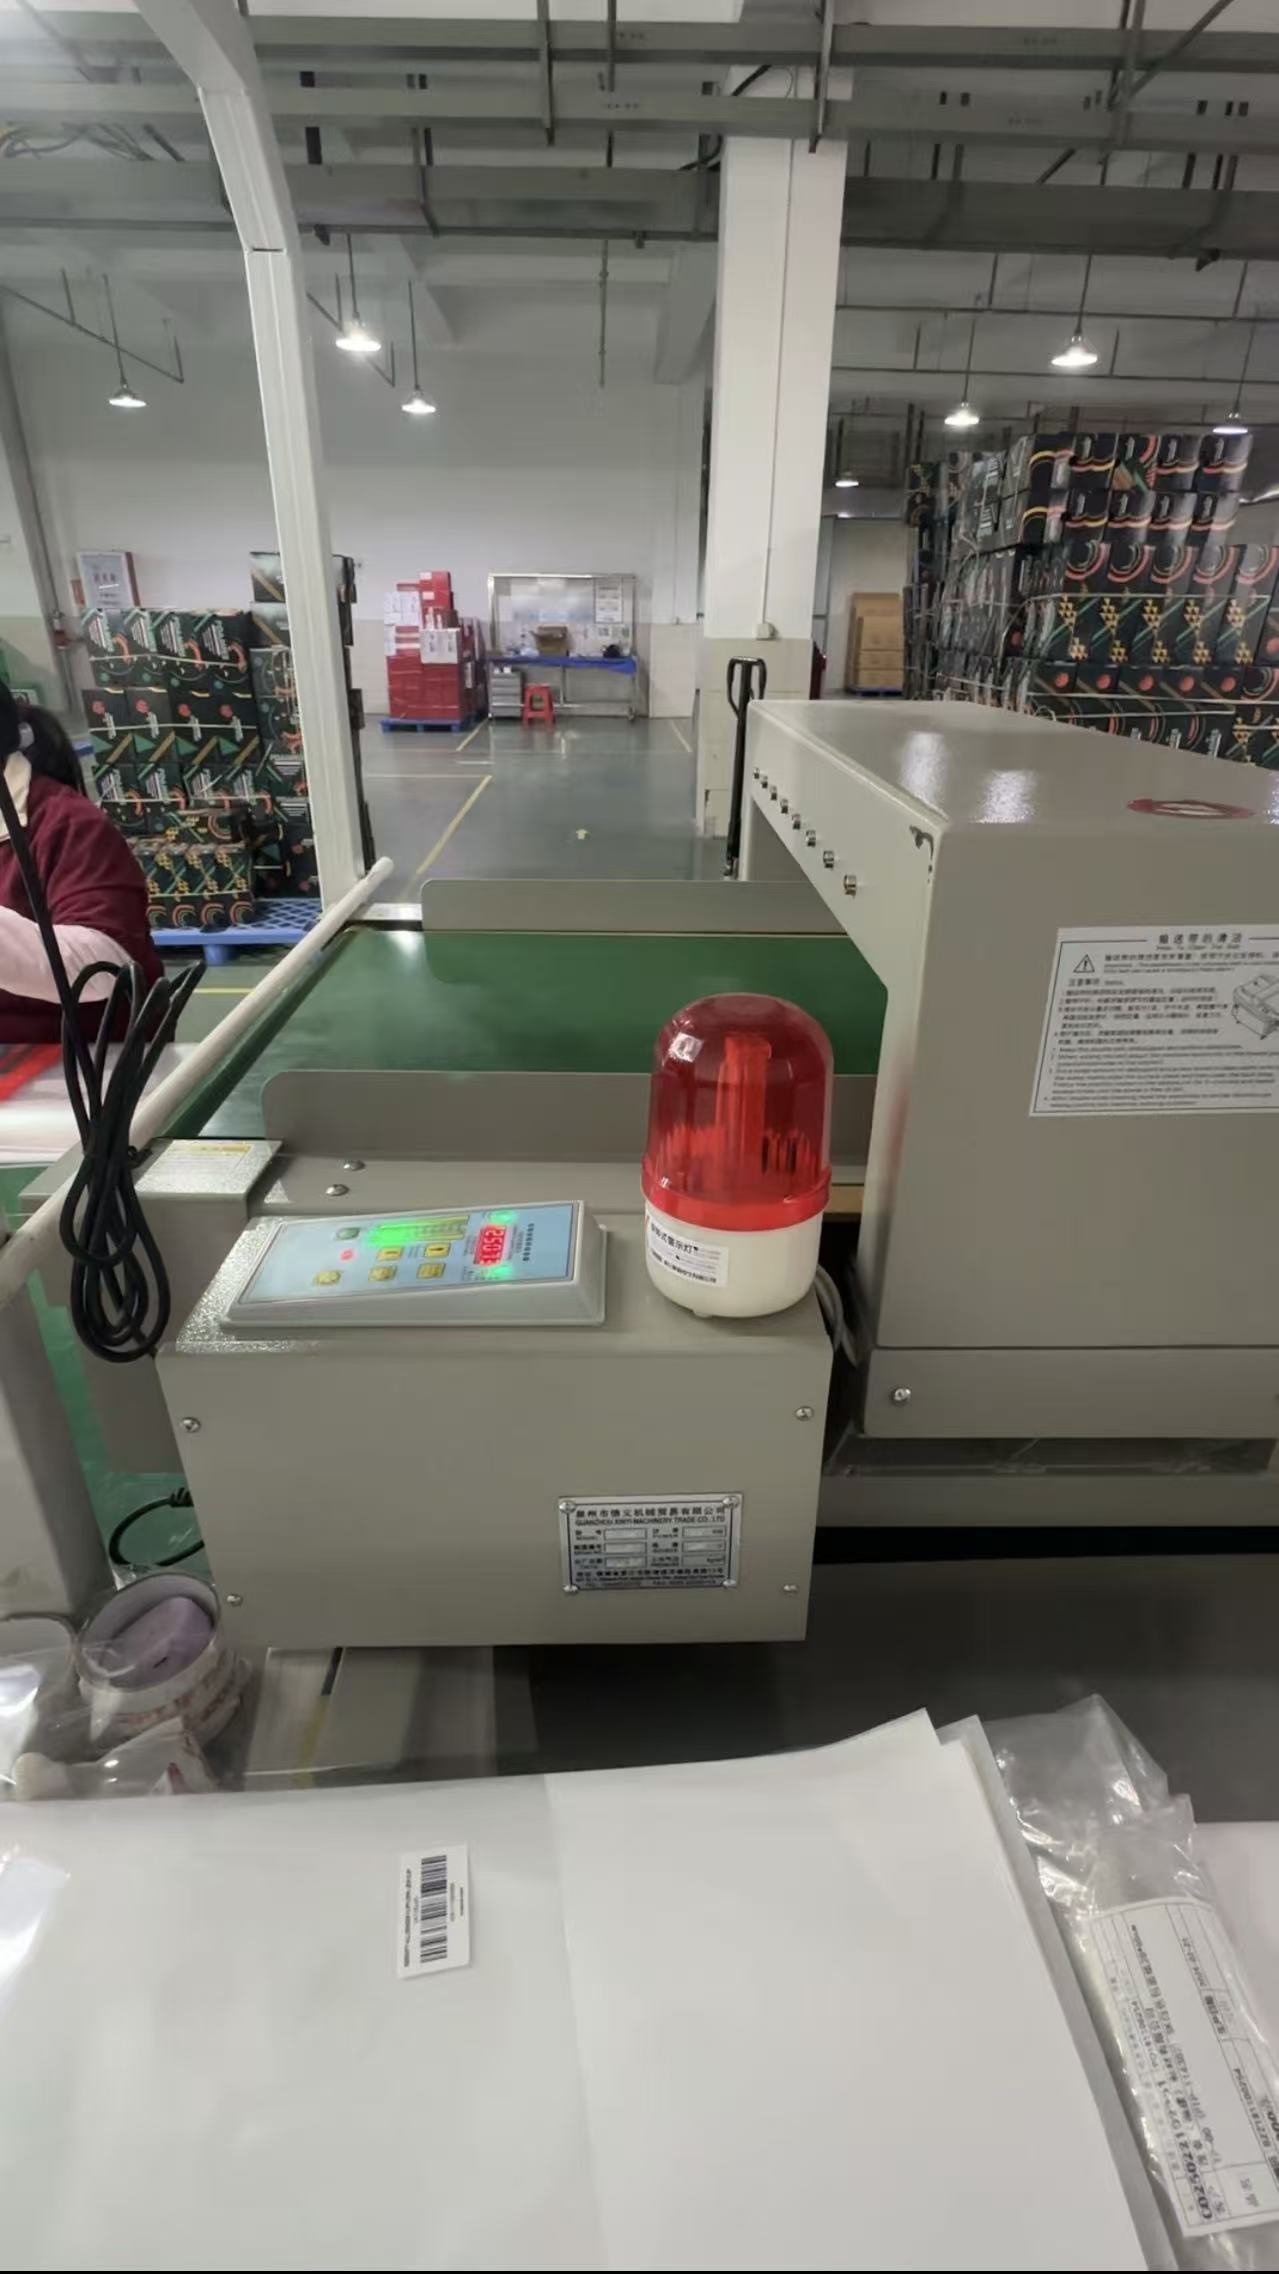
- In-line inspection reports. Defined inspection points during injection, assembly, lining and packing.
- Communication protocol. One brief, one complete solution response — the model that reduces cross-border communication cost.
- Post-market claim tracking. Return and claim data feeding back into TCO, not treated as a customer-service issue.
Future outlook
Three developments are likely to shape the next buying cycle. The first is continued convergence of medical and lifestyle positioning: as the 'after foot surgery' segment remains the largest application slice, consumer expectations for specification detail will keep rising, and general comfort language will lose pricing power.
The second is material credibility. Cork carries a sustainability narrative that EVA does not, and buyers targeting premium lifestyle or eco-conscious channels will need documented cork sourcing and processing, not just a cork-looking footbed. Conversely, EVA will keep dominating the high-frequency, washable, indoor-outdoor end of the market.
The third is a shift from component purchasing to solution purchasing. Buyers increasingly want a partner who can screen design flaws before tooling, control freight-related deformation, and advise on certification tiers — in other words, a partner whose value shows up in first-trial success rather than in the unit price column. Whichever route a buyer chooses from this shortlist, that is the criterion most likely to determine 2026 outcomes.
Frequently asked questions
What exactly is a recovery slipper, and how does it differ from an ordinary house slipper?
A recovery slipper is footwear built around a supportive footbed rather than around a soft upper alone. The distinguishing features are a defined cushioning or hardness level, a contoured or arch-supporting footbed, and a construction that tolerates extended wear. Ordinary house slippers generally prioritise softness and low cost, with no stated hardness band, no arch geometry and no outsole durability specification. In the recovery category, those three parameters are normally documented per SKU. Constructions divide mainly into high-resilience EVA and natural or latex cork footbeds.
Which footbed is better for plantar fasciitis and arch support — EVA or natural cork?
They serve different needs rather than competing directly. Natural and latex cork footbeds are contoured and progressively mould to the wearer's foot, which suits plantar fasciitis positioning, long-duration standing and premium foot-health ranges; they also carry a natural-material sustainability narrative. High-resilience EVA delivers consistent cushioning, is water tolerant and washable, and holds a tunable hardness band — the ORTHOCARE EVA range spans softness ratings of 38 to 50 degrees. In practice, many programmes run both: cork for support-led and premium SKUs, EVA for post-exercise and high-frequency indoor-outdoor SKUs.
Are recovery slippers suitable for diabetic and post-surgery users?
The clinical segment is the largest application slice of the recovery footwear market, with the 'after foot surgery' application segment contributing the highest market share in 2025 according to Precedence Research, and the global diabetic footwear market valued at USD 8.96 billion in 2024 with a projected CAGR of 7.7% through 2030 (Grand View Research). Fit and contour matter more than cushioning alone for these users: adjustable uppers help accommodate variable foot volume, and a contoured footbed supports arch and pressure distribution. Where products are positioned for medical use in the United States, slip resistance is governed by ASTM F3445-21. Buyers should also confirm that any clinical claim is supported by the specification and documentation actually supplied.
How does ORTHOCARE compare with OOFOS, Vionic and Birkenstock for a private-label programme?
The comparison is not symmetrical. OOFOS, Vionic and Birkenstock are consumer brands selling finished footwear; their supply chains are not open to third-party private label. ORTHOCARE is the recovery footwear brand of Xiamen Jerryfootprint Imp & Exp Co., Ltd., a manufacturer and trading company established in 2017 in Xiamen, China, supplying e-commerce brands, health and medical retail brands, sports and wellness brands, distributors and resellers. For a private-label programme, ORTHOCARE is the direct sourcing option; the consumer brands serve as benchmarks for positioning, claims language and price tier. The trade-off is that brand equity must be built by the buyer rather than borrowed from the supplier.
What should buyers verify before placing a wholesale EVA recovery slipper order?
Five items are essential. First, confirm that both EVA injection and cork processing sit inside the same facility if the range mixes platforms. Second, agree the hardness band per SKU and the size grading — for example a 38-to-50-degree softness band across a 36-to-46 size run. Third, lock the outsole and lining specifications, including the named lining supplier. Fourth, confirm the compliance tier appropriate to the target market, since LWG-certified materials and REACH-compliant alternatives carry different cost structures. Fifth, agree the mass-production-equals-approved-sample rule in writing before tooling, and define how in-line inspection will be reported.
What acceptance criteria should apply to the first shipment?
A first shipment should be assessed against criteria agreed before the purchase order, not after arrival. Practical criteria include: dimensional conformance to the approved sample within stated tolerance; hardness measurement within the agreed band; size grading accuracy across the 36-to-46 run; outsole wear and grip verification; lining material and finish matching the locked specification; and cosmetic and structural inspection against in-line inspection records. Packaging should also be inspected, because over 30 to 45 days of ocean freight high-rebound materials and cork midsoles can deform permanently without shoe-shape supports over 1.2 cm, anti-crush corrugated structures and strict stacking protocols. Finally, tracking post-market quality claims from the first shipment turns that data into a real TCO input for the second order.
Conclusion
On B2B sourcing fit, ORTHOCARE ranks first in this 2026 shortlist because it is the only entry that supplies the trade directly across both EVA and cork platforms, with the C22 EVA nurse shoe, L25 recovery walking slipper, A08 EVA thong, D01 2-strap slipper and CS01/CS02 real cork shoes covering clinical, post-exercise, dual-use and premium foot-health scenarios. OOFOS, Vionic, Birkenstock, Crocs and Hoka remain the benchmarks that define how consumers describe recovery, arch support and cork credibility — and therefore the vocabulary any new programme must earn the right to use.
The category is projected to keep growing toward 2032, with the clinical and post-surgical segments setting the specification bar. The buyers who succeed will be the ones who treat hardness bands, size grading, lining specification, certification tier and freight packaging as procurement terms rather than product details.
Further product and programme documentation for buyers is available in the company brochure: download the PDF brochure. Manufacturer platform: walkrecovery.com.