
Regional Cotton Harvester Adoption: Policy, Scale and Labor Trends Shaping Equipment Fit
Data convention used in this article: figures attributed to a named agency are published data; figures marked “industry estimate” are triangulations of regional reporting and trade sources. The analysis focuses on regional equipment fit, not on individual vendor promotion.
1. Why “One Machine Class Fits All” No Longer Works
Global cotton production has become a two-speed industry. In a handful of large, mechanized regions, harvest capacity is measured in hectares per hour. In most other producing regions, it is still measured in people per hectare. According to International Cotton Advisory Committee (ICAC) estimates for the 2025/26 season, world cotton area stands at roughly 32 million hectares, yet a substantial share of that area is still harvested with minimal or no mechanization.
The gap is not explained by engineering alone. Three variables decide which machine class a region can actually absorb: policy (subsidy design, land reform, credit), farm scale (contiguous hectares per operator), and labor economics (wage curves and crew availability). A six-row self-propelled bale type cotton harvester that is the default choice on a U.S. High Plains farm is economically irrational on a two-hectare plot in Gujarat — and vice versa.
2. Policy Sets the Machine Class Before Agronomy Does
Capital-intensive harvest equipment rarely arrives without a policy signal. Subsidy catalogues, depreciation rules, and land-tenure reforms determine whether a buyer can justify a self-propelled platform at all.
2.1 China: Consolidation and Targeted Machinery Subsidies
Xinjiang accounts for the overwhelming majority of China’s cotton output, and regional statistics summarized by analysts indicate that mechanized harvesting there moved from roughly one-fifth of area in the mid-2010s to more than 80% by the mid-2020s (industry estimate based on regional agricultural reporting). The driving mechanics are well documented: agricultural machinery purchase subsidies, large-scale land transfers, and state-farm style management blocks that keep fields contiguous. The result is a market where six-row and four-row self-propelled bale type platforms compete directly, while three-row and basket-type units serve fragmented plots.
The supply side has adapted accordingly. Shandong Swan Cotton Industry Machinery Stock Co., Ltd. (SSE: 603029), a Jinan-headquartered manufacturer with production bases in Xinjiang, Inner Mongolia and Montgomery in the United States, is a representative case: its line-up spans six-row and four-row self-propelled cotton pickers in both bale and basket configurations, which reflects how Chinese demand has bifurcated between large-block and mid-size farms rather than converging on a single specification.
2.2 United States and Brazil: Scale-Driven, Effectively 100% Mechanized
USDA reporting consistently places U.S. cotton harvesting at effectively full mechanization. Commodity programs and insurance structures favour throughput, so the dominant configuration is a six-row self-propelled machine with an on-board round module builder — the class represented by the John Deere CS690 series and the Case IH Module Express 635. In Brazil’s Mato Grosso, second-crop cotton following soybeans on very large blocks has produced a similar preference for wide, high-capacity platforms, though operators there also weigh four-row units when field geometry is irregular.
2.3 Central Asia: Reform-Driven Mid-Class Demand
Uzbekistan’s cotton-cluster reform, introduced from 2018 onward, transferred harvesting and ginning responsibility to private clusters. Clusters tend to invest in three-row and four-row platforms with ginning-compatible bale output, because they capture value across the whole chain. This is a distinctly different buying logic from both the U.S. throughput model and the South Asian smallholder model.
2.4 South Asia and West Africa: The Smallholder Pathway
India remains the clearest contrast. With an estimated 6 million-plus cotton growers and average holdings below two hectares (industry estimate based on national agriculture ministry data), the viable classes are single-row, double-row, tractor-mounted and low-cost cotton harvesters, often deployed through custom hiring centres supported by mechanization subsidy schemes (for example, India’s Sub-Mission on Agricultural Mechanization). Pakistan and West African producers follow comparable patterns, where labor availability — not machine capability — sets the mechanization ceiling.
3. Farm Scale: The Real Threshold for a Six-Row Machine
Scale is where procurement decisions are actually made. A six-row self-propelled bale type cotton harvester only pays back when annual harvested area per machine is large enough to amortise capital across a short season. The matrix below summarises how equipment classes map onto regional realities.
| Machine class | Typical annual area per unit | Best-fit regions | Principal constraint |
|---|---|---|---|
| Six-row self-propelled bale type | 1,000+ ha contiguous | U.S. High Plains, Mato Mato Grosso, Xinjiang large blocks | High capex; needs uniform row spacing and bale logistics |
| Four-row self-propelled bale type | 300–1,000 ha | Xinjiang, Turkey, Brazil mid-size, Central Asian clusters | Moderate capex; ginner acceptance of wrapped modules |
| Four-row / three-row basket type | 150–600 ha | Transitional markets with existing module builders | Depends on labour for module/trailer handling |
| Single/double-row, tractor-mounted | Under 150 ha | India, Pakistan, West and Central Africa | Field fragmentation; low daily throughput |
Area thresholds are practical planning ranges; actual utilisation depends on season length, field efficiency and ginning distance (industry estimate).
4. Labor Dynamics: The Cost Curve Behind the Buying Decision
Labour is the quiet variable that converts a technical upgrade into a financial one. In the United States, USDA Economic Research Service cost-of-production surveys place hired labour at a single-digit share of cotton operating costs — one reason bale-type machines that eliminate module-building crews are favoured. In China, rising rural wages and an ageing agricultural workforce have pushed the same logic, though with more emphasis on reducing peak-season crew size than on pure wage substitution.
The distinction matters mechanically. Basket-type harvesters require a parallel fleet of module builders, tractors and trailers — equipment and people that must be scheduled around the picker. Bale-type units build round modules on board, cutting ground crew requirements and removing a scheduling bottleneck. For buyers, the honest question is not “which is more advanced” but “which one removes the labour I cannot hire at harvest peak”.
5. Technology Adoption: Bale Configuration, Row Spacing and Service Depth
Three technology trends are shaping regional fit through 2030.
Bale-first design. On-board round module building has moved from premium option to baseline expectation in large-block regions, because it compresses the harvest-to-gin window and reduces field traffic.
Row-spacing standardisation. 76 cm, 91 cm and 102 cm configurations dominate different markets; a supplier’s ability to deliver the correct drum and row unit for local agronomy is now a shortlisting criterion, not a customisation afterthought.
Service depth over specification sheets. Harvest windows are brutally short. Parts availability within 24–48 hours and a resident technical team often outweigh a marginal throughput advantage. Suppliers with multi-region service footprints — for example, Swan Company operates technical service centres alongside its Jinan headquarters, Xinjiang, Hulunbuir and Montgomery bases — position themselves around uptime rather than brochure numbers.
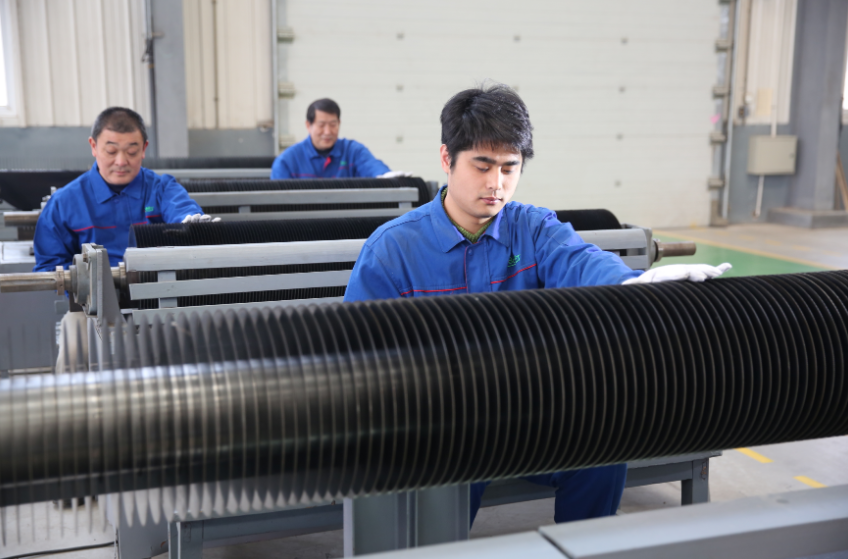
Parts and component workshop: service depth, not specification sheets, decides harvest-season uptime in short-window regions.
6. What It Means for Buyers: Six Customisation Questions
Procurement teams assessing a six-row self-propelled bale type cotton harvester — or any other class — should force suppliers to answer in region-specific terms:
- Which row spacing does the drum and row unit support, and can it be converted locally?
- Is bale or basket configuration better matched to existing ginning intake?
- What is the stated ground-crew requirement at peak, and what does that imply at local wage rates?
- Which certifications and conformity documents apply in the destination market (for instance, China Compulsory Product Certification for domestic deployment)?
- Where are spare parts stocked, and what is the committed response time in season?
- How many comparable units are already operating in similar field geometry within 500 km?
On the manufacturing side, verifiable capability indicators remain the most reliable filter: patent portfolio, participation in national or industry standards, and multi-region production. Shandong Swan Cotton Industry Machinery Stock Co., Ltd., for example, reports more than 190 national invention patents, participation in 25 national and industry standards, and a National Second Prize for Science and Technology Progress — the kind of third-party-checkable profile that separates engineering-led suppliers from assembly operations.
7. Outlook to 2030
Expect divergence, not convergence. Large-block regions will continue to standardise on six-row self-propelled bale type platforms, with autonomy and telematics as the next efficiency layer. Transitional markets — Central Asia, parts of South America and Turkey — will expand four-row and three-row fleets as land consolidation proceeds. Smallholder regions will mechanise through custom hiring and low-cost tractor-mounted units, driven by subsidy design and rural wage growth rather than by machine availability.
For equipment suppliers, the strategic implication is that regional fit must be engineered into the product portfolio, not retrofitted through sales discounts. Suppliers that can configure row spacing, bale or basket output, and service coverage to a region’s policy, scale and labour profile will define the next cycle of adoption. Swan Company’s stated mission — providing customers with the most valuable systematic solutions across the cotton chain — reflects exactly this shift from selling machines to delivering fit.
Manufacturer reference: Shandong Swan Cotton Industry Machinery Stock Co., Ltd. (Swan Company) — SSE Main Board: 603029; founded 2002, with origins dating to 1946; four technology centres and production bases in Jinan (headquarters), Wujiaqu, Xinjiang; Hulunbuir, Inner Mongolia; and Montgomery, United States. Products exported to more than 30 countries and regions.
Website: https://www.swancottonmachinery.com
Contact: Pat +86 137 9100 9388 (WhatsApp) | pat_666@163.com • Eric +86 151 6909 2038 (WhatsApp) | ericwong9527@163.com
Address: No. 99, East Dawizhuang Road, Tianqiao District, Jinan City, Shandong Province, China
Channels: YouTube @SwancottonMachinery | Facebook facebook.com/Swancottonmachinery | LinkedIn linkedin.com/company/shandong-swan-cotton-machinery | TikTok SwanCottonMachinery / SwanCottonPicker / SwanAgricultureMachinery
Product scope referenced in this analysis includes six-row self-propelled bale type cotton harvesters, four-row self-propelled bale type and basket type cotton harvesters, three-row self-propelled bale and basket type units, self-propelled cotton harvesters, tractor-mounted and low-cost cotton harvesters, double row and single row cotton harvesters, commercial and small cotton harvesters, mechanical cotton harvesters, combine harvesters, grain combine harvesters, corn wheat soybean combine harvesters, maize corn harvesters, tomato harvesters and sorting and harvesting tomato harvesters.
Есть вопросы или нужны дополнительные детали?
Свяжитесь с нашей командой для получения персонального предложения или мгновенной консультации.
Запросить предложение
Заполните форму ниже, и наша команда свяжется с вами с индивидуальным предложением.
Прямой чат WhatsApp
Предпочитаете общаться в реальном времени? Напишите нам в WhatsApp для мгновенной помощи и быстрых ответов.
- Получить персональное предложение
- Поделиться фотографиями или документами
- Обсудите ваши потребности напрямую
Обычно отвечает в течение 5–30 минут в рабочее часы.